



[ad_1]
Simply as Netflix and Tesla disrupted the media and automotive trade, many fintech corporations are reworking the Monetary Providers trade by profitable the hearts and minds of a digitally lively inhabitants by personalised providers, numberless bank cards that promise extra safety, and frictionless omnichannel experiences. NuBank’s success story as an eight-year previous startup changing into Latin America’s most beneficial financial institution shouldn’t be an remoted case; over 280 different fintechs unicorns are additionally keen to disrupt your entire cost trade. As famous within the Monetary Conduct Authority (FCA) research, “There are indicators that a number of the historic benefits of huge banks could also be beginning to weaken by innovation, digitization and altering client habits.” Confronted with the selection of both disrupting or being disrupted, many conventional monetary providers establishments (FSIs) like JP Morgan Chase have not too long ago introduced important strategic investments to compete with fintech corporations on their very own grounds – on the cloud, utilizing knowledge and synthetic intelligence (AI).
Given the amount of knowledge required to drive superior personalization, the complexity of working AI from experiments (proof of ideas/POCs) to enterprise scale knowledge pipelines, mixed with strict knowledge and privateness laws on using buyer knowledge on cloud infrastructure, Lakehouse for Monetary Providers has rapidly emerged because the strategic platform for a lot of disruptors and incumbents alike to speed up digital transformation and supply hundreds of thousands of consumers with personalised insights and enhanced banking experiences (see how HSBC is reinventing cellular banking with AI).
In our earlier answer accelerator, we confirmed establish manufacturers and retailers from bank card transactions. In our new answer accelerator (impressed from the 2019 research of Bruss et. al. and from our expertise working with international retail banking establishments), we capitalized on that work to construct a contemporary hyper-personalization knowledge asset technique that captures a full image of the buyer and goes past conventional demographics, revenue, product and providers (who you’re) and extends to transactional habits and procuring preferences (the way you financial institution). As a knowledge asset, the identical will be utilized to many downstream use circumstances, akin to loyalty applications for on-line banking purposes, fraud prevention for core banking platforms or credit score threat for “purchase now pay later” (BNPL) initiatives.
Transactional context
Whereas the widespread method to any segmentation use case is an easy clustering mannequin, there are only some off-the-shelf strategies. Alternatively, when changing knowledge from its unique archetype, one can entry a wider vary of strategies that always yield surprising outcomes. On this answer accelerator, we convert our unique card transaction knowledge into graph paradigm and leverage strategies initially designed for Pure Language Processing (NLP).
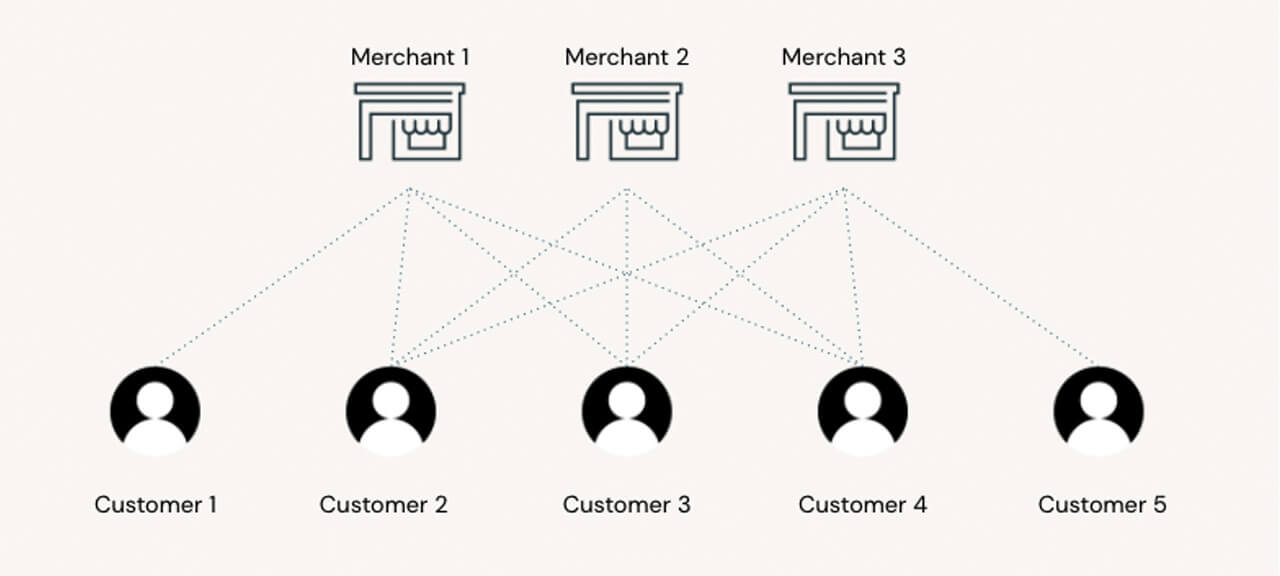
Just like NLP strategies the place the that means of a phrase is outlined by its surrounding context, a service provider’s class will be realized from its buyer base and the opposite manufacturers that their shoppers help. In an effort to construct this context, we generate “procuring journeys” by simulating prospects strolling from one store to a different, up and down our graph construction. The goal is to study “embeddings,” a mathematical illustration of the contextual data carried by the purchasers in our community. On this instance, two retailers contextually shut to at least one one other can be embedded into massive vectors which are mathematically shut to at least one one other. By extension, two prospects exhibiting the identical procuring habits will probably be mathematically shut to at least one one other, paving the best way for a extra superior buyer segmentation technique.
Service provider embeddings
Word2Vec was developed by Tomas Mikolov, et. al. at Google to make the neural community coaching of the embedding extra environment friendly, and has since turn into the de facto commonplace for growing pre-trained phrase embedding algorithms. In our answer, we’ll use the default wordVec mannequin from the Apache Spark™ ML API that we practice in opposition to our procuring journeys outlined earlier.
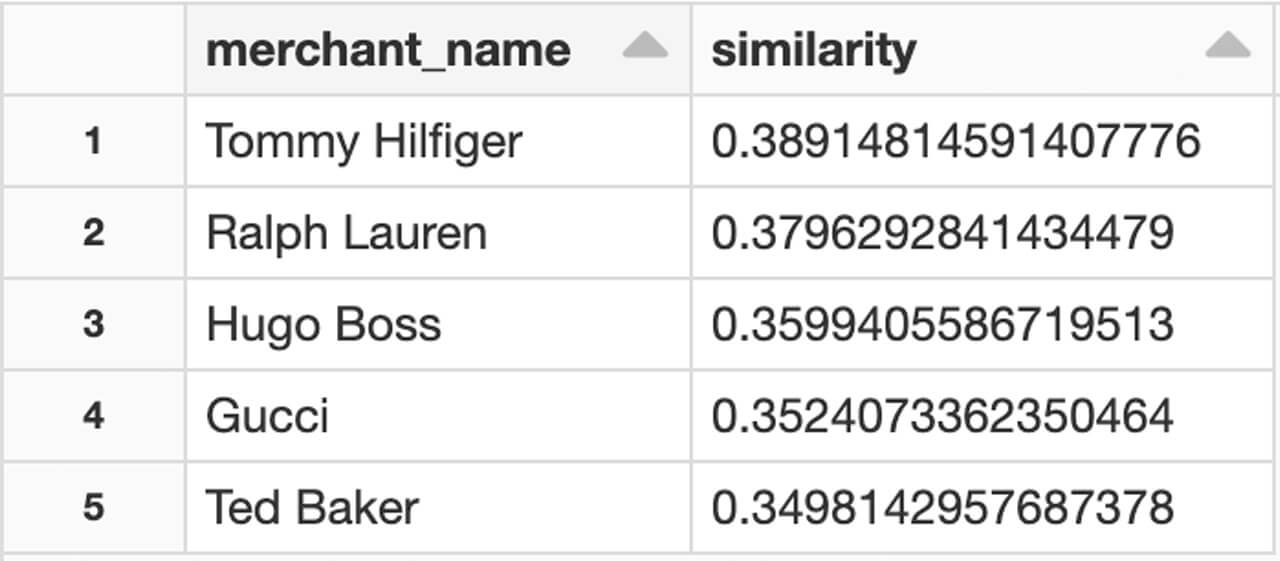
from pyspark.ml.characteristic import Word2Vec with mlflow.start_run(run_name="shopping_trips") as run: word2Vec_model = Word2Vec() .setVectorSize(255) .setWindowSize(3) .setMinCount(5) .setInputCol('walks') .setOutputCol(vectors) .match(shopping_trips) mlflow.spark.log_model(word2Vec_model, "mannequin")The obvious solution to rapidly validate our method is to eyeball its outcomes and apply area experience. On this instance of manufacturers like “Paul Smith”, our mannequin can discover Paul Smiths’ closest rivals to be “Hugo Boss”, “Ralph Lauren” or “Tommy Hilfiger.”
We didn’t merely detect manufacturers inside the similar class (i.e. vogue trade) however detected manufacturers with an identical price ticket. Not solely might we classify completely different traces of companies utilizing buyer behavioral knowledge, however our buyer segmentation may be pushed by the standard of products they buy. This statement corroborates the findings by Bruss et. al.
Service provider clustering
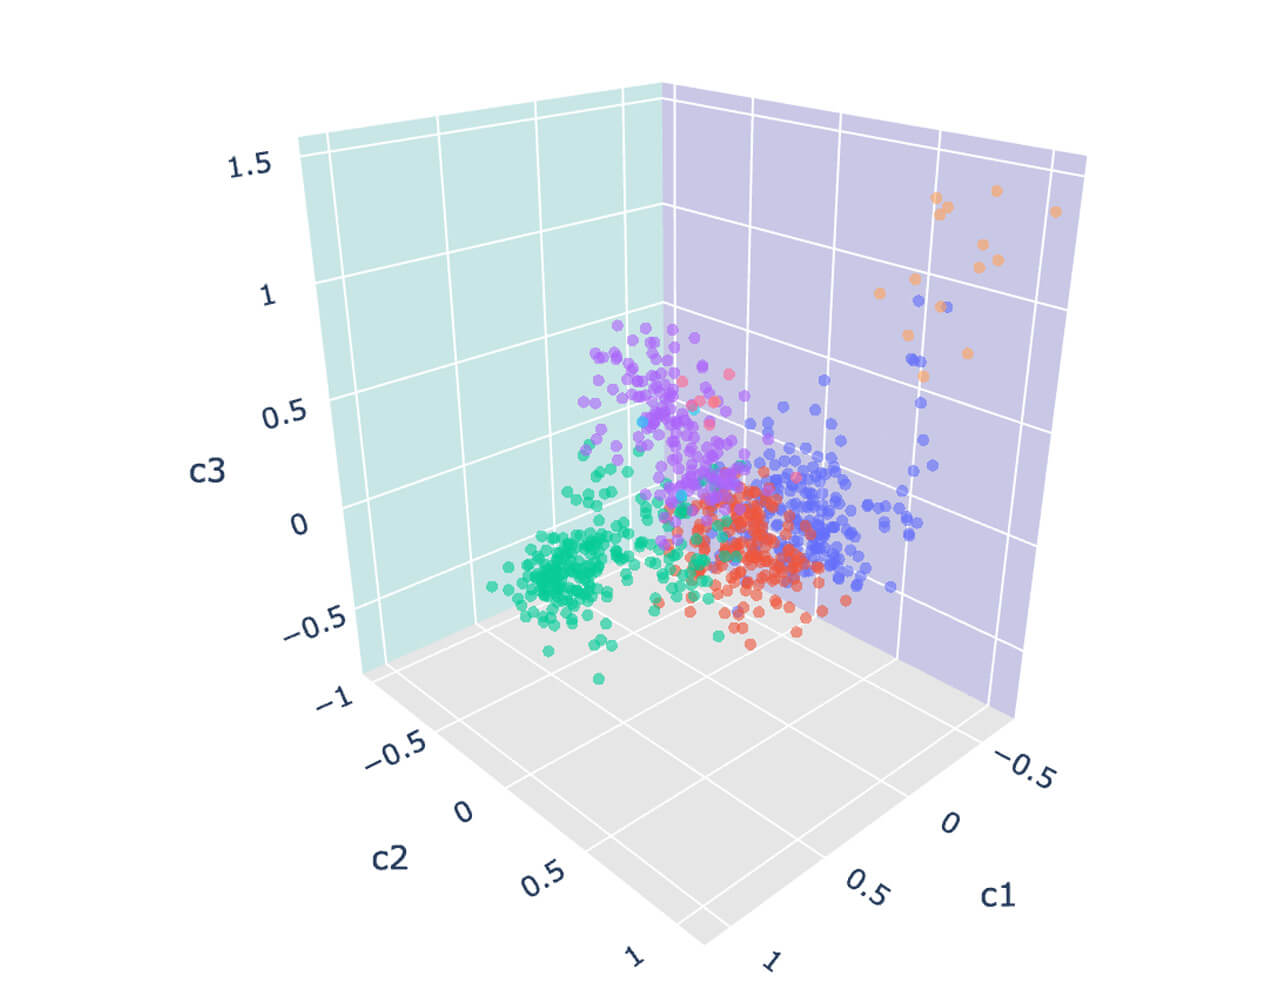
Though the preliminary outcomes had been troubling, there is perhaps teams of retailers roughly related than others that we could wish to establish additional. The simplest solution to discover these important teams of retailers/manufacturers is to visualise our embedded vector house right into a 3D plot. For that objective, we apply machine studying strategies like Principal Part Evaluation (PCA) to cut back our embedded vectors into 3 dimensions.
Utilizing a easy plot, we might establish distinct teams of retailers. Though these retailers could have completely different traces of enterprise, and could appear dissimilar at first look, all of them have one factor in widespread: they appeal to an identical buyer base. We are able to higher verify this speculation by a clustering mannequin (KMeans).
Transactional fingerprints
One of many odd options of the word2vec mannequin is that sufficiently massive vectors might nonetheless be aggregated whereas sustaining excessive predictive worth. To place it one other manner, the importance of a doc might be realized by averaging the vector of every of its phrase constituents (see whitepaper from Mikolov et. al.). Equally, buyer spending preferences will be realized by aggregating vectors of every of their most popular manufacturers. Two prospects having related tastes for luxurious manufacturers, high-end vehicles and effective liquor would theoretically be near each other, therefore belonging to the identical phase.
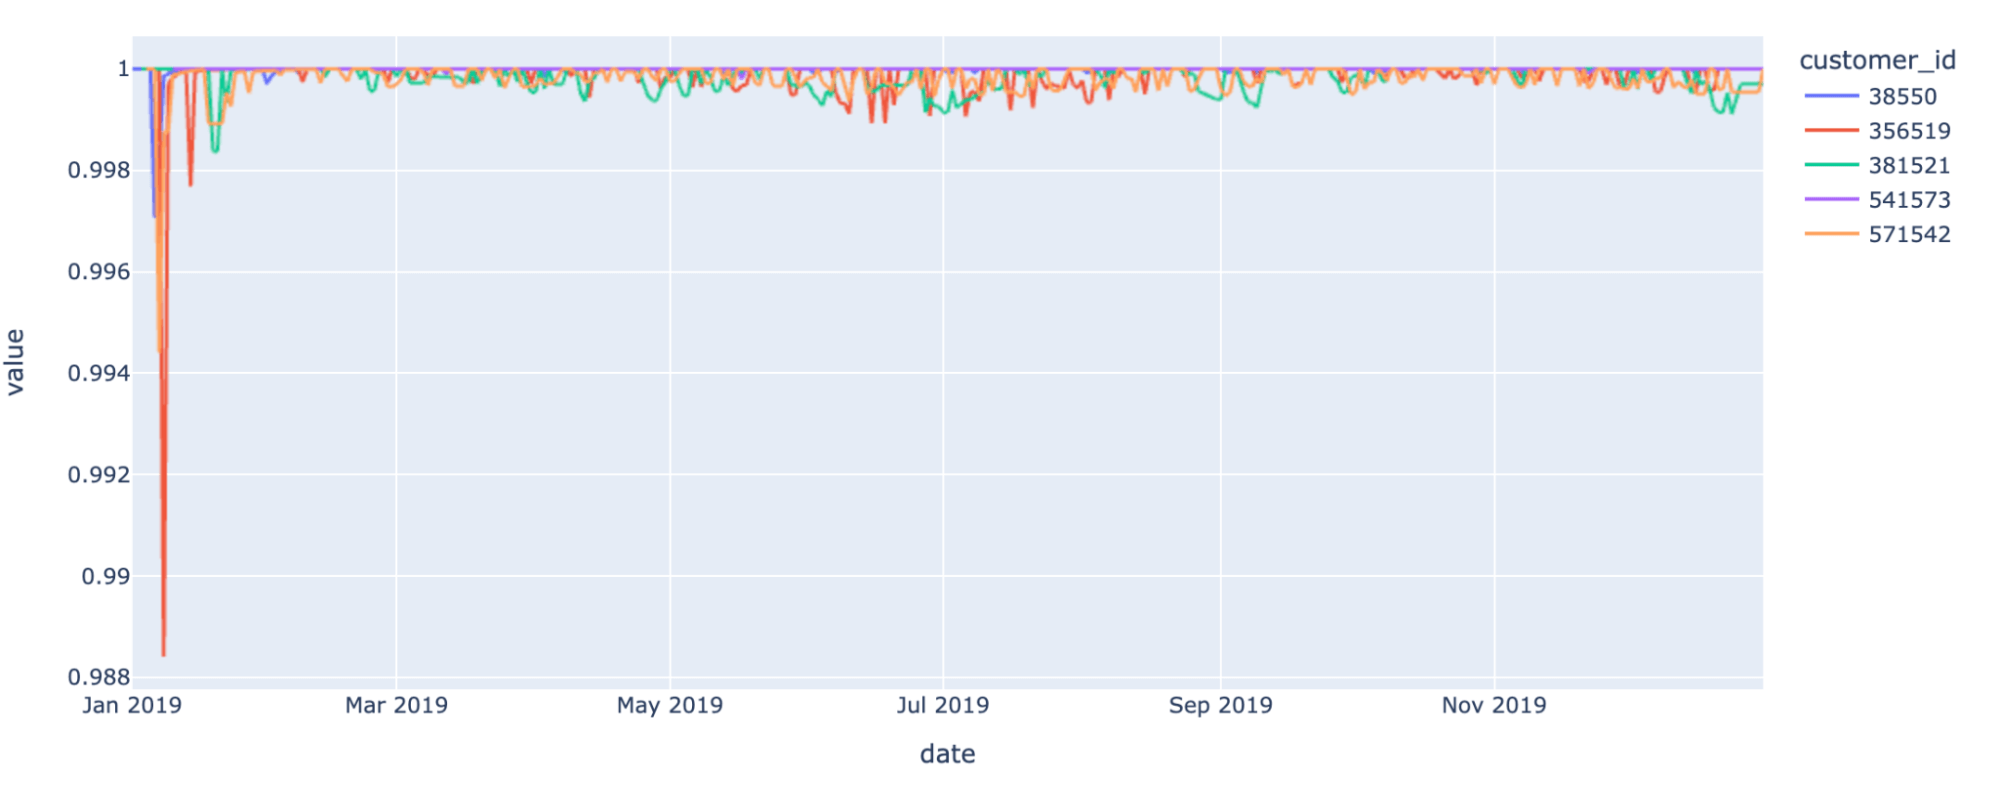
customer_merchants = transactions .groupBy('customer_id') .agg(F.collect_list('merchant_name').alias('walks')) customer_embeddings = word2Vec_model.remodel(customer_merchants)It’s price mentioning that such an aggregated view would generate a transactional fingerprint that’s distinctive to every of our finish shoppers. Though two fingerprints could share related traits (similar procuring preferences), these distinctive signatures can be utilized to trace distinctive particular person buyer behaviors over time.
When a signature drastically differs from earlier observations, this might be an indication of fraudulent actions (e.g. sudden curiosity for playing corporations). When signature drifts over time, this might be indicative of life occasions (having a new child youngster). This method is vital to driving hyper-personalization in retail banking: the flexibility to trace buyer preferences in opposition to real-time knowledge will assist banks present personalised advertising and gives, akin to push notifications, throughout varied life occasions, constructive or detrimental.
Buyer segmentation
Though we had been in a position to generate some sign that provides nice predictive worth to buyer behavioral analytics, we nonetheless haven’t addressed our precise segmentation drawback. Borrowing from retail counterparts which are typically extra superior on the subject of buyer 360 use circumstances together with segmentation, churn prevention or buyer lifetime worth, we are able to use a unique answer accelerator from our Lakehouse for Retail that walks us by completely different segmentation strategies utilized by best-in-class retail organizations.
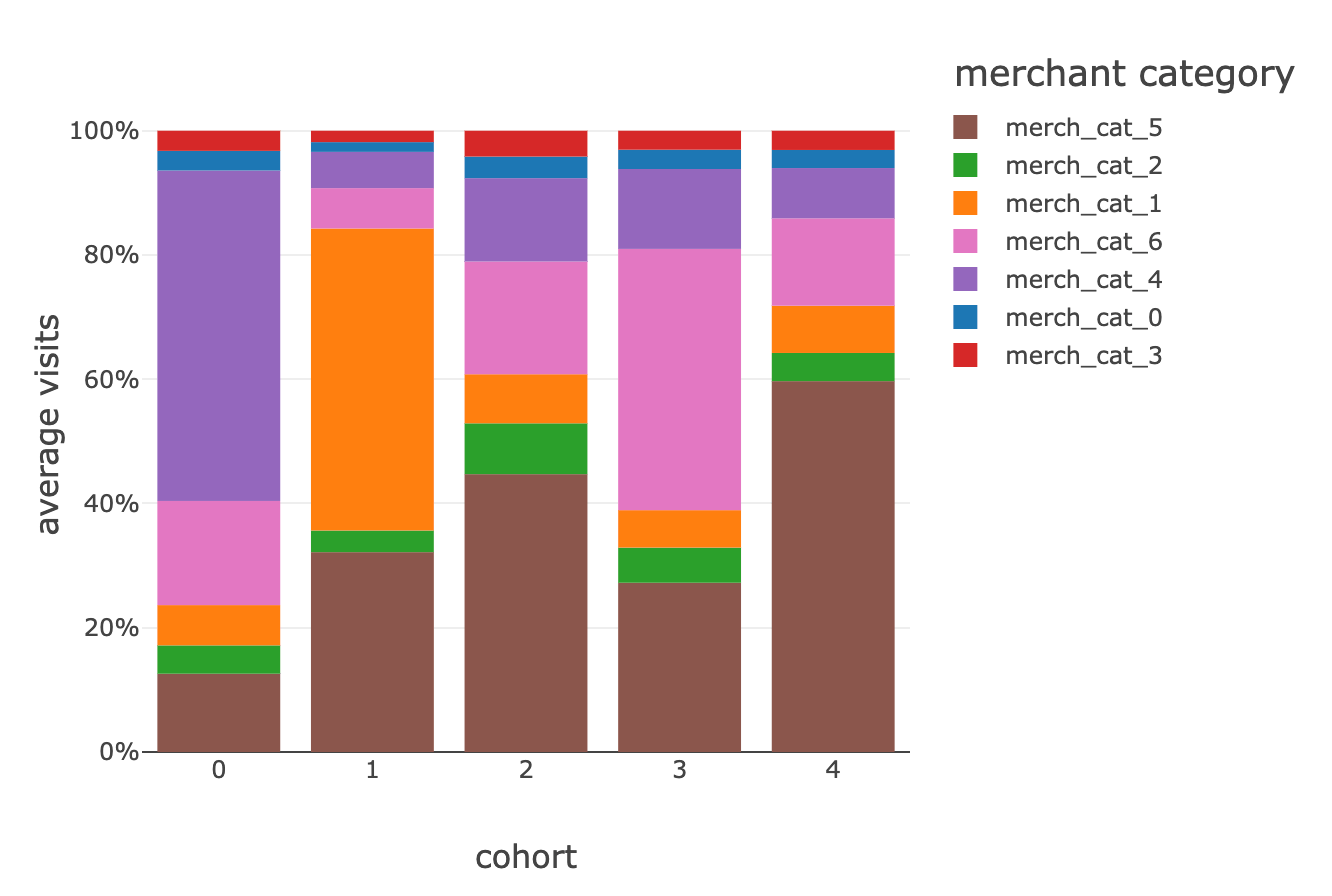
Following retail trade finest practices, we had been in a position to phase our total buyer base in opposition to 5 completely different teams exhibiting completely different procuring traits.
Whereas cluster #0 appears to be biased in direction of playing actions (service provider class 4 within the above graph), one other group is extra centered round on-line companies and subscription-based providers (service provider class 6), in all probability indicative of a youthful era of consumers. We invite our readers to enrich this view with extra knowledge factors they already find out about their prospects (unique segments, services, common revenue, demographics, and so on.) to raised perceive every of these behavioral pushed segments and its impression for credit score decisioning, next-best motion, personalised providers, buyer satisfaction, debt assortment or advertising analytics.
Closing ideas
On this answer accelerator, now we have efficiently utilized ideas from the world of NLP to card transactions for buyer segmentation in retail banking. We additionally demonstrated the relevance of the Lakehouse for Monetary Providers to deal with this problem the place graph analytics, matrix calculation, NLP, and clustering strategies should all be mixed into one platform, secured and scalable. In comparison with conventional segmentation strategies simply addressed by the world of SQL, the disruptive way forward for segmentation builds a fuller image of the buyer and may solely be solved with knowledge + AI, at scale and in actual time.
Though we’ve solely scratched the floor of what was potential utilizing off-the-shelf fashions and knowledge at our disposal, we proved that buyer spending patterns can extra successfully drive hyper-personalization than demographics, opening up an thrilling vary of latest alternatives from cross-sell/upsell and pricing/focusing on actions to buyer loyalty and fraud detection methods.
Most significantly, this system allowed us to study from new-to-bank people or underrepresented shoppers with out a recognized credit score historical past by leveraging data from others. With 1.7 billion adults worldwide who don’t have entry to a checking account in accordance with the World Financial Discussion board, and 55 million underbanked within the US alone in 2018 in accordance with the Federal Reserve, such an method might pave the best way in direction of a extra customer-centric and inclusive future for retail banking.
Attempt the accelerator notebooks on Databricks to check your buyer 360 knowledge asset technique right this moment and contact us to study extra about how now we have helped prospects with related use circumstances.
[ad_2]

