


[ad_1]
Monetary processes and merchandisers want an improve in consciousness to money in on youthful shoppers’ in-store buying loyalty.
Embedded inside the altering economic system are elementary variations within the shopping for and banking mores of youthful shoppers in comparison with older constituents. Assembly the wants of three important overlapping shopper teams can go a great distance in how prospects view their buying choices. Companies can not afford to disregard their quirks and habits shifts when buying.
Two of essentially the most influential shopper generations are millennials, aka Gen Y (ages 27-42) and Gen Z (ages 18-24). Packed inside these age teams is a lesser-recognized section of buyers tagged as Zillennials. This tag-along shopping for drive is a micro-generation that sits in between.
Zillennials establish with key elements of the millennial and Gen Z buying expertise. However many banks and entrepreneurs contemplate them too younger or too previous to totally take part in social or cultural norms, which may very well be a expensive and misguided resolution.
As bodily shops get pleasure from a return of foot site visitors from youthful shoppers, their banking and fee preferences current challenges to retailers. Gen Z doesn’t need to should name somebody or anticipate an e-mail response to finish easy duties, like updating an tackle, locking or unlocking their bank card, or disputing a transaction.
The one must-have to cater to Gen Z prospects is easy self-service by means of a cellular app, based on Sagar Rajgopal, president and chief buyer officer at Ubiquity, a customer support and enterprise course of outsourcing supplier headquartered in New York Metropolis.
“Banks want agility if they’re going to meet the wants and calls for of Gen Z prospects. Omnichannel capabilities ought to embody self-service through an app, chatbots, reside chat, in-app messaging, and a reside agent over the cellphone. Banks that present a seamless buyer expertise and nice buyer assist will likely be effectively positioned to seize this technology,” he informed the E-Commerce Occasions.
Youthful Shoppers Welcome New Fee Strategies
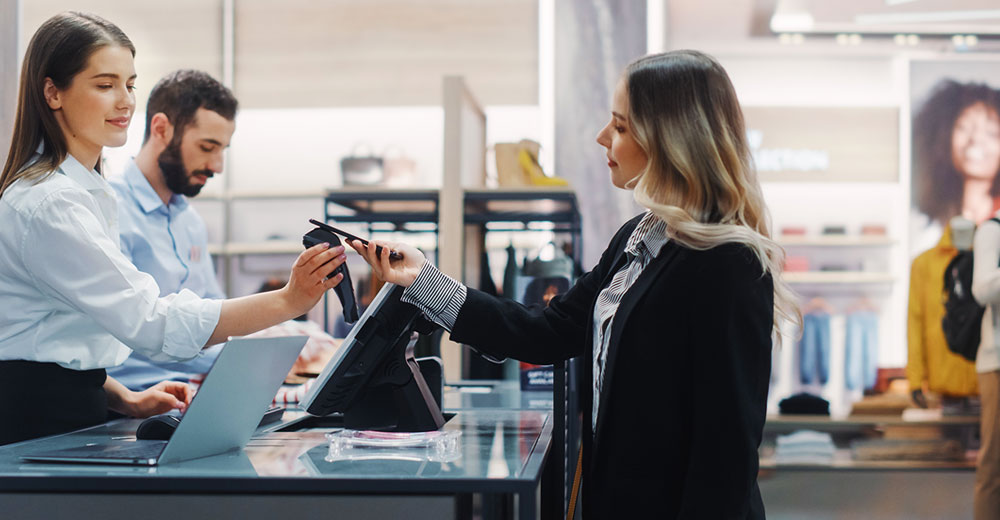
At present’s altering economic system includes two sides of the identical cash coin — retaining returning prospects on e-commerce websites and fanning the flames of in-store buying. Each might be served by offering assist for new fee strategies, comparable to digital wallets, to supply the absolute best checkout expertise.
Regardless of the continued rise of e-commerce and on-line buying, youthful shoppers nonetheless need to make in-store purchases. Digital wallets and biometric fee strategies are essential for creating the absolute best fee expertise for youthful shoppers, prompt Peter Galvin, chief product officer at world fee enablement platform NMI.
These digital choices encourage them to make extra purchases in-store. New information from NMI discovered that 83% of shoppers ages 18-24 and 87% of shoppers ages 25-40 stated they’re all the time excited to attempt new fee strategies.
Zillennials are much more more likely to make in-store purchases than millennials. Youthful shoppers nonetheless need to have the ability to use the handy, tech-first fee choices they get pleasure from on-line when making in-store purchases, as they already really feel snug with these digital fee strategies. That units the trail for what this shopper section needs.
“Retailers, the impartial software program vendor (ISVs), and impartial gross sales organizations (ISOs) who companion with retailers to allow these fee experiences should guarantee their fee programs are geared up to deal with this new period of funds whether or not it’s in-store, on-line, or on a cellular system,” stated Galvin.
New Banking Course of Wanted Too
Tweens, teenagers, and 20-somethings comprise 68 million shoppers whose banking actuality is far completely different from how their dad and mom began out utilizing monetary providers. Catering to this burgeoning Gen Z shopper base requires a contemporary method to buyer expertise (CX).
Why? Greater than half (54%) of Gen Z shoppers will drop an organization after a single destructive buyer expertise. That sort of “See Ya” shopper flip-off shouldn’t be restricted to product purchases, both.
Banking for digital natives bears little resemblance to their dad and mom’ habits, noticed Rajgopal. Latest analysis discovered that 83% of Gen Z shoppers are pissed off with financial institution processes. Due to this fact, along with digital providers and choices, banks additionally have to take an intensive have a look at and use a contemporary method to buyer expertise to seize and keep loyalty from youthful shoppers.
“In contrast to banking of the previous, 90% of Gen Z’s digital banking interactions happen on smartphones. Partly due to this digital-first mindset, this younger technology shouldn’t be wed to conventional banking,” he noticed. “By pairing cellular banking options with a contemporary method to buyer expertise, banks can differentiate their manufacturers throughout generations,” he famous.
Shoppers Ripe for New, Less complicated Digital Choices
NMI’s Funds Innovation Pulse Report confirmed that round half of shoppers ages 18-24 (53%), 25-40 (57%), and 41-56 (46%) use fee purposes for in-store purchases. Clearly, Gen Z shoppers are way more snug with cellular funds and digital wallets than these of older generations.
“Amongst respondents ages 57 and older, lower than 1 / 4 of those older respondents do,” Galvin stated. “Proper now, youthful shoppers desire cellular and digital funds, and so they anticipate these choices to be accessible to them in nearly all fee situations.”
Youthful shoppers in the present day will merely stroll away from a purchase order if the fee course of is just too complicated, time-consuming, or troublesome for them. The journey from discovering the merchandise they need, swiping their card, or tapping their cellphone must be fast and painless for them, he insisted.
“In in the present day’s powerful economic system, each buyer is essential, so companies can not afford to lose a sale,” he added.
A severe consideration right here is the truth that many youthful shoppers don’t carry money. Some don’t even carry a bodily credit score or debit card anymore, famous Galvin. However they are going to nearly all the time have their cellphone.
“So implementing cellular and digital funds will help be certain that youthful shoppers all the time have a fee technique accessible to them,” he stated.
Devising New Tips for the Banking Commerce
Banks have a task to play in serving to youthful shoppers deal with their monetary literacy, based on Ubiquity’s Rajgopal. Departure from conventional tedious brick-and-mortar transactions additionally presents a colossal alternative for shops to enhance the CX they supply.
“Cellular banking apps are non-negotiable for Gen Z. The excellent news is that what’s going to attraction to them shouldn’t be more likely to be a turn-off for different demographics,” he prompt. “The other is true.”
Digital interfaces should be filled with interesting visuals, easy-to-access sources, and full performance. However companies can not ignore their net portal for these prospects preferring it.
Product and have units ought to give attention to monetary wellness and supply useful ideas to assist younger shoppers achieve their monetary footing, he provided, including that those self same options will also be helpful to older shoppers.
“The largest distinction will likely be in how and what you market versus wholesale variations in your product set,” stated Rajgopal.
For instance, 65% of Gen Z shoppers use social media to tell their buying choices. Reaching them on their social platforms of alternative goes to be crucial, in addition to monitoring your individual model critiques on-line and in social channels.
Mother and father Consider Additionally
For youthful Gen Z shoppers who nonetheless reside at dwelling, banks ought to contemplate concentrating on their dad and mom, based on Rajgopal. That’s what fintech organizations like Greenlight, GoHenry, Step, and a few banks are doing.
Focusing on dad and mom with monetary instruments explicitly developed for digitally savvy teenagers who’re beginning to earn cash by means of chores or part-time jobs is sensible.
ADVERTISEMENT
“Mother and father need to supply guardrails and monetary schooling for his or her kids, and the teenagers need easy, participating digital experiences that mirror different manufacturers they love whereas empowering them to buy,” he stated.
All prospects need to really feel like their financial institution has their again. However it’s very true for Gen Z prospects residing paycheck-to-paycheck.
“Banks that present providers like budgeting and private monetary administration instruments that assist Gen Z shoppers make smarter monetary choices can construct belief and loyalty,” added Rajgopal.
Enterprise Boundaries to Including Fee Choices
Offering a number of types of digital funds can supply selections to shoppers. However an excessive amount of alternative can create quite a lot of confusion, Galvin warned.
“The extra varieties there are, the better the chance that buyers really feel confused with the choices accessible to them,” he defined.
A crowded checkout can result in shoppers not realizing which choice is greatest for them, can delay the checkout course of, and reduce buyer satisfaction. If prospects are confused or pissed off at checkout, they could take their enterprise elsewhere as they prioritize velocity and comfort when paying.
One or two digital or cellular choices may herald new gross sales and be an excellent different for youthful shoppers. Nevertheless, it’s not all the time fast and simple for companies to implement a number of strategies.
Implementing a number of varieties can get to be costly and time-consuming. This may be very true if the enterprise is attempting to perform these strategies themselves with out the assistance of an ISV or ISO companion that may present steering and experience into the technical aspect of integration, famous Galvin.
[ad_2]

