


[ad_1]
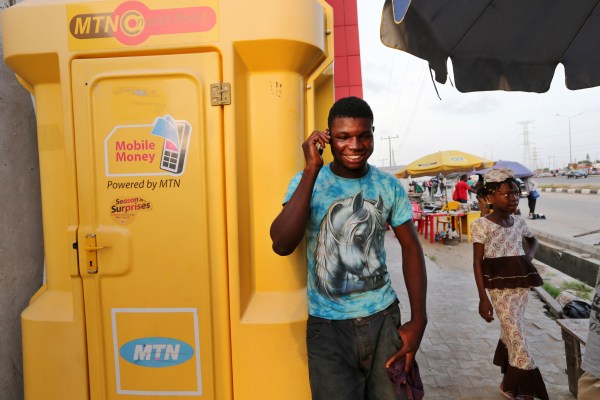
Africa’s mobile-money sector stays essentially the most energetic of any area on the planet in line with GSM Affiliation (GSMA), an umbrella physique representing the pursuits of gamers within the telecommunications business.
The report exhibits that registered cellular cash accounts in Africa stood at barely over half a billion in 2020, a 12-percentage level progress from the earlier 12 months. The worth of transactions hit $495 billion, up 23-percentage factors.
East Africa accounts for the majority of Africa’s cellular cash transactions adopted by West Africa. The GSMA report exhibits that the worth of transactions in West Africa had the best progress after growing by 46 share factors to $178billion (the second highest worth after East Africa’s).
Basically, cellular cash permits customers to ship and obtain cash, in addition to to pay utility payments — however in superior conditions like it’s throughout Africa, the pockets turns subscribers’ telephone numbers right into a type of proxy for financial institution accounts.
Because it grows, cellular cash has come to be a launchpad for digital lenders, who use clients’ cellular cash transaction historical past to find out the quantity of on the spot credit score to increase to debtors — monies which can be then straight deposited into clients’ cellular cash wallets.
MTN Uganda’s cellular overdraft credit score
Revolutionary merchandise grounded on cellular cash embody the newly-launched MoMoAdvance, an overdraft mortgage by MTN Uganda, the nation’s greatest telco, and a subsidiary of the MTN Group — whose different affiliated corporations have operations in southern, west and central areas of Africa.
MoMoAdvance was launched following a pilot program that began late 2020, and it permits MTN’s clients to overdraw on its MoMo (cellular cash) pockets. Customers shall be charged an entry charge of two.75% of the quantity borrowed, and a every day curiosity of 0.5% on the excellent steadiness for a most of 45 days.
“MTN MoMoAdvance will provide the MTN MoMo clients the comfort of transacting past their MoMo pockets steadiness and pay again later… we imagine that it’s going to give them the comfort to transact seamlessly past their pockets balances throughout occasions of want then pay again later,” mentioned MTN Cell Monetary Providers, Common Supervisor, Stephen Mutana.
MoMoAdvance borrows closely from an analogous overdraft product, Fuliza, by Kenya’s greatest telco, Safaricom, which was launched in January 2019, and permits subscribers to finish transactions even after they have inadequate funds of their M-Pesa cellular wallets.
The overdraft providers are based mostly on a borrowing restrict that’s outlined by a buyer’s transaction historical past, whereas the overdrawn quantity and accrued curiosity are deducted from the shoppers’ wallets anytime they’re topped up. Fuliza has grown in recognition over the past three years amongst M-Pesa customers, with Safaricom now giving out about $12 million price of overdraft loans day-after-day.
Fuliza is obtainable in partnership with KCB and NCBA, each of that are Kenyan banks with a regional presence. MTN Uganda additionally partnered with NCBA for its MoMoAdvance credit score, and it’s now possible that the financial institution will set up such partnerships in different East African nations Rwanda and Tanzania, the place it already has operations.
The mobile-money overdraft merchandise are offering a aggressive edge to telcos as lending apps proceed to enter African markets. The apps have stepped up competitors for telco-owned cellular lending providers like MoKash by MTN Uganda and M-Shwari by Safaricom – which permit clients to borrow short-term loans and pay again inside 30 days.
Such revolutionary and simply accessible digital lending providers have made credit score accessible to a majority of individuals in Africa, who have been beforehand minimize out by formal monetary establishments for lack of a banking historical past. Nonetheless, a lot of the rising digital lenders cost predatory pursuits, usually attributed to the high-risk atmosphere that they work in. That is because the regulatory atmosphere regularly adapts to formalize the sector, finally main to raised pricing for customers whereas shielding the service suppliers from losses.
[ad_2]

