


[ad_1]
What’s worse than discovering out that identification thieves took out a 546 p.c curiosity payday mortgage in your title? How a few 900 p.c curiosity mortgage? Or how about not studying of the fraudulent mortgage till it will get handed off to assortment brokers? One reader’s nightmare expertise spotlights what can occur when ID thieves and hackers begin concentrating on on-line payday lenders.
The reader who shared this story (and copious documentation to go together with it) requested to have his actual title omitted to keep away from encouraging additional assaults in opposition to his identification. So we’ll simply name him “Jim.” Final Might, somebody utilized for some sort of mortgage in Jim’s title. The request was doubtless despatched to a web based portal that takes the borrower’s mortgage software particulars and shares them with a number of potential lenders, as a result of Jim mentioned over the subsequent few days he obtained dozens of emails and calls from lenders desirous to approve him for a mortgage.
Many of those lenders had been keen to present Jim cash as a result of they had been charging exorbitant 500-900 p.c rates of interest for his or her loans. However Jim has lengthy had a safety freeze on his credit score file with the three main shopper credit score reporting bureaus, and not one of the lenders appeared prepared to proceed with out at the very least a peek at his credit score historical past.
Among the many firms that checked to see if Jim nonetheless wished that mortgage he by no means utilized for final Might was Mountain Summit Monetary (MSF), a lending establishment owned by a Native American tribe in California referred to as the Habematelol Pomo of Higher Lake.
Jim instructed MSF and others who referred to as or emailed that identification thieves had utilized for the funds utilizing his title and knowledge; that he would by no means take out a payday mortgage; and would they please take away his info from their database? Jim says MSF assured him it might, and the mortgage was by no means issued.
Jim spent months checking out that mess with MSF and different potential lenders, however after some time the inquiries died down. Then on Nov. 27 — Thanksgiving Day weekend — Jim obtained a collection of rapid-fire emails from MSF saying they’ve obtained his mortgage software, that they’d permitted it, and that the funds requested had been now accessible on the checking account laid out in his MSF profile.
Curiously, the fraudsters had taken out a mortgage in Jim’s title with MSF utilizing his actual e-mail tackle — the identical e-mail tackle the fraudsters had used to impersonate him to MSF again in Might 2021. Though he didn’t technically have an account with MSF, their authentication system is predicated on e-mail addresses, so Jim requested {that a} password reset hyperlink be despatched to his e-mail tackle. That labored, and as soon as contained in the account Jim might see extra concerning the mortgage particulars:
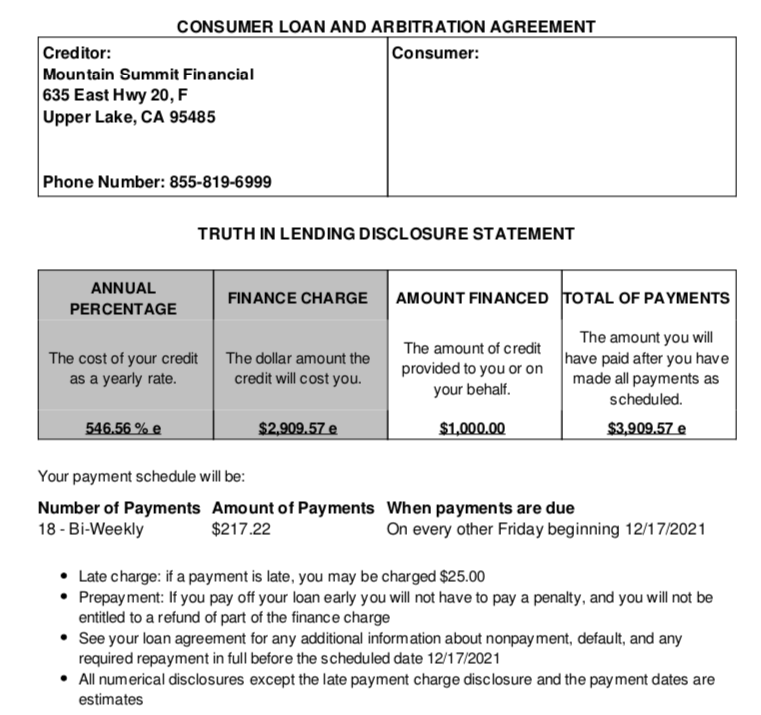
The phrases of the unauthorized mortgage in Jim’s title from MSF.
Check out that 546.56 p.c rate of interest and finance costs listed on this $1,000 mortgage. When you pay this mortgage off in a yr on the instructed bi-weekly cost quantities, you should have paid $3,903.57 for that $1,000.
Jim contacted MSF as quickly as they opened the next week and came upon the cash had already been dispersed to a Financial institution of America account Jim didn’t acknowledge. MSF had Jim fill out an affidavit claiming the mortgage was the results of identification theft, which necessitated submitting a report with the native police and a variety of different steps. Jim mentioned quite a few calls to Financial institution of America’s fraud crew went nowhere as a result of they refused to debate an account that was not in his title.
Jim mentioned MSF finally agreed that the mortgage wasn’t professional, however they couldn’t or wouldn’t inform him how his info obtained pushed by way of to a mortgage — despite the fact that MSF was by no means capable of pull his credit score file.
Then in mid-January, Jim heard from MSF through snail mail that they’d found an information breach.
“We imagine the outsider could have had a possibility to entry the accounts of sure prospects, together with your account, at which level they’d be capable to view private info pertaining to that buyer and doubtlessly acquire an unauthorized mortgage utilizing the shopper’s credentials,” MSF mentioned.
MSF mentioned the non-public info concerned on this incident could have included title, date of delivery, government-issued identification numbers (e.g., SSN or DLN), checking account quantity and routing quantity, house tackle, e-mail tackle, cellphone quantity and different normal mortgage info.
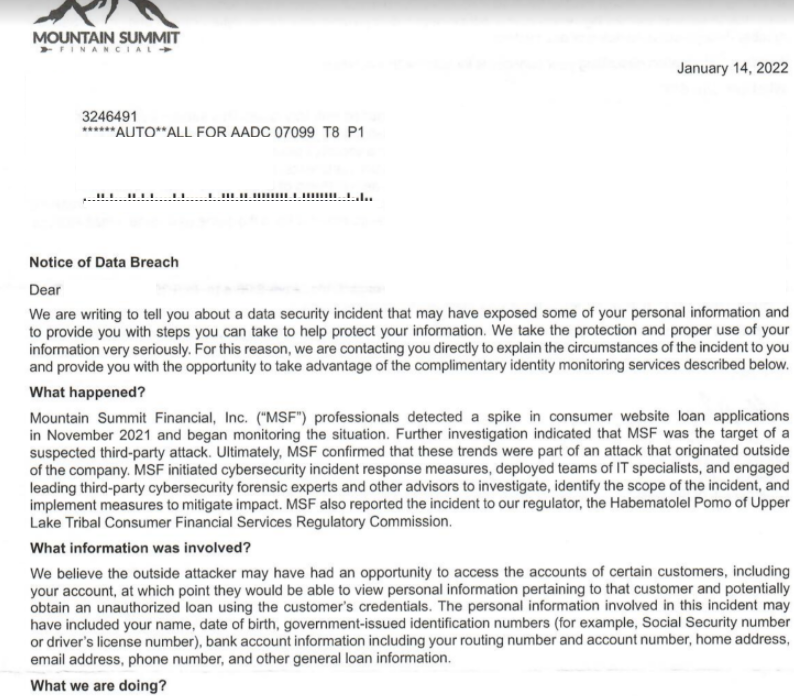
A portion of the Jan. 14, 2022 breach notification letter from tribal lender Mountain Summit Monetary.
Nevermind that his info was solely in MSF’s system due to an earlier try by ID thieves: The intruders had been capable of replace his current (never-deleted) document with new banking info after which push the appliance by way of MSF’s methods.
“MSF was the goal of a suspected third-party assault,” the corporate mentioned, noting that it was working with the FBI, the California Sheriff’s Workplace, and the Tribal Fee for Lake County, Calif. “Finally, MSF confirmed that these traits had been a part of an assault that originated exterior of the corporate.”
MSF has not responded to questions concerning the aforementioned third occasion or events which may be concerned. However it’s attainable that different tribal lenders might have been affected: Jim mentioned that not lengthy after the phony MSF payday mortgage was pushed by way of, he obtained at the very least three inquiries in fast succession from different lenders who had been impulsively inquisitive about providing him a mortgage.
In a press release despatched to KrebsOnSecurity, MSF mentioned it was “the sufferer of a malicious assault that originated exterior of the corporate, by unknown perpetrators.”
“As quickly as the difficulty was uncovered, the corporate initiated cybersecurity incident response measures to guard and safe its info; and notified legislation enforcement and regulators,” MSF wrote. “Moreover, the corporate has notified people whose private identifiable info could have been impacted by this crime and is actively working with legislation enforcement in its investigation. As that is an ongoing felony investigation, we will make no further remark right now.”
In accordance with the Native American Monetary Companies Affiliation (NAFSA), a commerce group in Washington, D.C. representing tribal lenders, the short-term installment mortgage merchandise provided by NAFSA members are usually not payday loans however slightly “installment loans” — that are amortized, have a particular mortgage time period, and require funds that go towards not simply curiosity, however that additionally pay down the mortgage principal.
NAFSA didn’t reply to a number of requests for remark.
Practically all U.S. states have usury legal guidelines that restrict the quantity of curiosity an organization can cost on a mortgage, however these limits historically haven’t utilized to tribal lenders.
Leslie Bailey is a workers lawyer at Public Justice, a nonprofit authorized advocacy group in Oakland, Calif. Bailey says an rising variety of on-line payday lenders have sought affiliations with Native American tribes in an effort to reap the benefits of the tribes’ particular authorized standing as sovereign nations.
“The reason being clear: Real tribal companies are entitled to ‘tribal immunity,’ which means they will’t be sued,” Bailey wrote in a weblog submit. “If a payday lender can protect itself with tribal immunity, it could hold making loans with illegally-high rates of interest with out being held accountable for breaking state usury legal guidelines.”
Bailey mentioned in a single frequent sort of association, the lender gives the required capital, experience, workers, know-how, and company construction to run the lending enterprise and retains a lot of the income. In change for a small p.c of the income (normally 1-2%), the tribe agrees to assist draw up paperwork designating the tribe because the proprietor and operator of the lending enterprise.
“Then, if the lender is sued in court docket by a state company or a gaggle of cheated debtors, the lender depends on this paperwork to say it’s entitled to immunity as if it had been itself a tribe,” Bailey wrote. “Any such association — generally referred to as ‘rent-a-tribe’ — labored effectively for lenders for some time, as a result of many courts took the company paperwork at face worth slightly than peering backstage at who’s actually getting the cash and the way the enterprise is definitely run. But when current occasions are any indication, authorized panorama is shifting in direction of elevated accountability and transparency.”
In 2017, the Shopper Monetary Safety Bureau sued 4 tribal on-line payday lenders in federal court docket — together with Mountain Summit Monetary — for allegedly deceiving customers and gathering debt that was not legally owed in lots of states. All 4 firms are owned by the Habematolel Pomo of Higher Lake.
The CFPB later dropped that inquiry. However a category motion lawsuit (PDF) in opposition to those self same 4 lenders is continuing in Virginia, the place a gaggle of plaintiffs have alleged the defendants violated the Racketeer Influenced and Corrupt Organizations Act (RICO) and Virginia usury legal guidelines by charging rates of interest between 544 and 920 p.c.
In accordance with Buckley LLP, a monetary companies legislation agency based mostly in Washington, D.C., a district court docket dismissed the RICO claims however denied the protection’s movement to compel arbitration and dismiss the case, ruling that the arbitration provision was unenforceable as a potential waiver of the debtors’ federal rights and that the defendants couldn’t declare tribal sovereign immunity. The district court docket additionally “held the mortgage agreements’ alternative of tribal legislation unenforceable as a violation of Virginia’s sturdy public coverage in opposition to unregulated lending of usurious loans.”
Buckley notes that on Nov. 16, 2021, the U.S. Court docket of Appeals for the Fourth Circuit upheld the district court docket ruling, concluding that the arbitration clauses within the mortgage agreements “impermissibly pressure debtors to waive their federal substantive rights beneath federal shopper safety legal guidelines, and contained an unenforceable tribal choice-of-law provision as a result of Virginia legislation caps normal rates of interest at 12 p.c.”
Jim mentioned he realized of the Thanksgiving weekend MSF mortgage solely as a result of the hackers apparently figured it was simpler to push by way of loans utilizing current MSF buyer account info than it was to change something within the data apart from the checking account for receiving the funds.
However had the hackers modified the e-mail tackle, Jim may need first came upon concerning the mortgage when the gathering businesses got here calling. And by then, his exorbitant mortgage can be in default and racking up some depraved late costs.
Jim says he’s nonetheless hopping mad at MSF, and lately he’s simply ready for the opposite shoe to drop.
“They issued this mortgage in my title with out verification and with out even checking my credit score in any respect, despite the fact that they had been already on discover that they shouldn’t have been coping with me from the Might incident,” Jim mentioned. “I nonetheless really feel like I’m going to get that decision sooner or later from a group company asking why I haven’t been making funds on some installment mortgage I by no means requested for.”
[ad_2]

