


[ad_1]

Patrick Rauland
•
February 8, 2023
One of many perks of an eCommerce enterprise is you can usually get began with little or no upfront prices. However in some unspecified time in the future, practically everybody with a rising enterprise has to think about financing. A financial enhance empowers you to put money into important assets on your firm, resembling stock, advertising, and expertise.
With out enough financing, your eCommerce enterprise might wrestle to compete or fail to succeed in its full potential. On this article, we’ll discover the fundamentals of financing for eCommerce companies, what financing choices are on the desk, and whenever you would possibly use every of those financing choices that will help you develop.
TLDR for Financing
For those who’re on the lookout for the quick and candy reply there are some guidelines of thumb which is able to assist:
When Is it Time to Pursue Financing Choices?
Earlier than you pursue financing, you need to decide if it’s the appropriate time on your firm.
Search Financing When Your Enterprise Is Established
If you wish to entry capital, your enterprise wants to have the ability to present progress and ideally revenue. The longer your organization has been working and creating wealth, the higher. If your enterprise is lower than six months previous, it is going to be tough to safe financing. However if you happen to’ve been working for greater than two years, you’ll have a neater time accessing a number of financing choices for eCommerce companies.
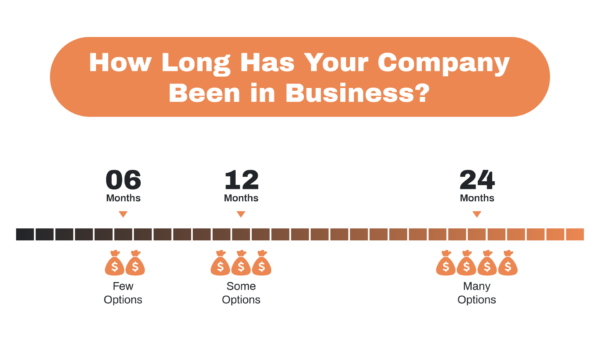
It’s higher to have a mixture of financing choices accessible to you, as choices can abruptly grow to be unavailable or change considerably. For instance, a financial institution that provides small enterprise loans might exit of enterprise, or a bank card firm might change its phrases and rates of interest.
We had our [line of credit] pulled in September 2020 with zero discover […] Fortunately, we have been in a position to purchase a while, get an SBA 7a mortgage to pay it off, and get away unscathed apart from numerous stress and wasted time.
-An ECF Discussion board member
Search Financing When You Have Time To Pursue It
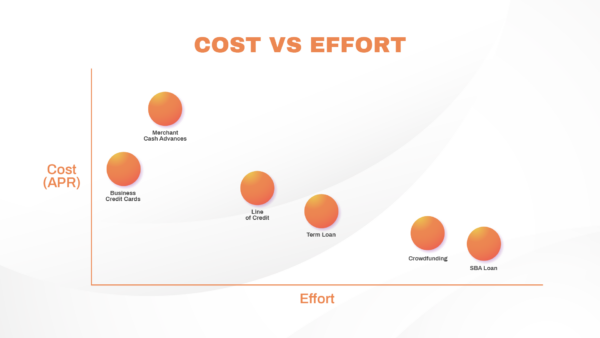
Financing is usually a trade-off between the cash you’ll get and the work it takes to safe it. Low-cost financing choices, resembling loans from conventional banks, require vital effort and time to safe, together with detailed enterprise plans, monetary projections, and private ensures.
Alternatively, bank cards or service provider money advances, could also be simpler to acquire however include increased charges and rates of interest. Because of this, eCommerce companies should weigh the prices and advantages of various financing choices and select the one that most closely fits their wants and targets.
Banks, Credit score Unions, and SBA Loans
Native banks and credit score unions are sometimes the most suitable choice for low-cost and dependable financing. These establishments sometimes supply a spread of financing choices, together with time period loans, strains of credit score, and entry to Small Enterprise Administration (SBA) loans.
Whereas it might take a while to discover a financial institution or credit score union that understands the distinctive wants of an eCommerce enterprise, the trouble is normally value it. Native banks and credit score unions usually have extra versatile lending standards and higher phrases than bigger, nationwide banks. They’re additionally extra more likely to work with eCommerce retailers to tailor a financing resolution to their particular wants.
Banks and credit score unions supply 4 frequent financing choices for eCommerce retailers:
- Time period Loans: The lender gives a lump sum of cash that have to be repaid over a hard and fast time frame, sometimes with mounted month-to-month funds.
- Line of Credit score: The lender gives a most amount of cash the borrower can entry and use as wanted. Curiosity is charged solely on the quantity borrowed.
- SBA Mortgage: The lender facilitates a mortgage offered by the Small Enterprise Administration
- Asset-based lending: The lender makes use of the borrower’s belongings, resembling stock or accounts receivable, as collateral to safe the mortgage.
Time period Mortgage vs. Line of Credit score
When deciding between a time period mortgage and a line of credit score, retailers ought to contemplate their particular wants and targets.
A time period mortgage is an effective possibility for retailers who want a particular amount of cash to fund a particular undertaking or buy, resembling shifting to a brand new warehouse or shopping for new tools. One of these financing gives a lump sum of cash that have to be repaid over a hard and fast time frame, sometimes with mounted month-to-month funds.
Some time period loans from ECF members:
| Financial institution | Fee | Restrict |
| Chase | Prime + 2-3% | 100k |
A line of credit score is an effective possibility for retailers who want ongoing entry to funds to cowl variable bills or benefit from alternatives as they come up. One of these financing gives a most amount of cash that the borrower can entry and use as wanted.
Curiosity is barely charged on the quantity borrowed. For those who don’t draw from the road of credit score, you then received’t pay any curiosity, which is extremely useful when money stream turns into tight.
One of the best time to get a financial institution LOC is whenever you don’t want it (significantly).
-An ECF Discussion board Member
Some strains of credit score from ECF members:
| Financial institution | Fee | Restrict |
| Financial institution of America | Prime + 4% | 500k |
| PNC Financial institution | Prime + 4.5% | 5M |
| Truist | Prime + 0.75% | 175k |
| Fifth Third | 3.26% | 500k |
SBA Loans
The Small Enterprise Administration (SBA) provides a number of several types of loans:
- 7(A)
- CDC – 504
- CAP Strains
- Export Loans
- Microloans
- Catastrophe Loans
The 7(A) mortgage is the preferred possibility. It gives working capital of as much as $5 million for companies which have an honest credit score rating and may present a down fee of 10-20%. It may be used for a wide range of functions, together with buying tools, refinancing debt, improving a enterprise, or shopping for a enterprise.
The Neighborhood Growth Company or CDC/504 mortgage is particularly designed to buy owner-occupied actual property. The phrases of this mortgage require the borrower to occupy not less than 51% of the area for his or her enterprise, and the mortgage is usually structured with the financial institution lending as much as 50%, the neighborhood growth company lending as much as 40%, and the borrower offering the remaining 10% as a down fee.
The SBA CAP Line is a line of credit score of as much as $5 million that can be utilized along side a 7(A) or 504 mortgage. These strains of credit score are helpful for eCommerce retailers who have to finance seasonal working capital or buy orders.
The SBA Export Mortgage is a mortgage of as much as $5 million that’s particularly designed to assist American companies export their merchandise abroad. These loans have among the finest charges and phrases accessible by way of the SBA.
The SBA Microloan is a small mortgage of as much as $50,000, with the common mortgage being $13,000. These loans are designed to supply eCommerce retailers with entry to capital for small-scale initiatives or purchases.
Lastly, the SBA Catastrophe Mortgage is accessible to companies in declared catastrophe areas to assist them recuperate from the consequences of the catastrophe.
Discovering and Securing an SBA Mortgage
Not all banks course of SBA loans. You should utilize the SBA’s lender experiences web site to discover a listing of banks which have made SBA loans prior to now and begin contacting them.
You will need to keep in mind that the SBA mortgage course of will be very time-consuming and require detailed documentation, so it is very important begin early and be ready. One ECF member mentioned this:
At instances, it felt like a 2nd job to get it completed.
For those who do get turned down for an SBA mortgage it implies that particular financial institution didn’t wish to take the danger. You may at all times apply once more by way of one other financial institution.
Some SBA loans from ECF members:
| Kind of Mortgage | Fee | Restrict |
| 504 | 2-3% | 810k for 25 years |
| 504 | 2.9% | 1.6M for 25 years |
Asset Primarily based Lending
Asset-based lending is a kind of financing that makes use of the belongings of a enterprise as collateral for a mortgage. With asset-based lending, the lender evaluates the worth of a enterprise’s belongings (resembling stock, tools, and accounts receivable) to find out the mortgage quantity the enterprise can qualify for.
With asset based mostly lending your most quantity of capital modifications frequently alongside together with your belongings and accounts receivable. Some banks would require updates in your stock each month. One of these lending is advantageous if in case you have a rising enterprise, for the reason that most quantity of capital will develop with you.
Andrew interviewed David Golob about The World of Asset Primarily based Lending on the podcast. Give it a pay attention if you wish to study extra. ????
Some asset based mostly lending loans from ECF members:
| Fee | Restrict |
| Prime + 0.5% | 3.5M |
| 4% | 1.5M |
Credit score Playing cards
A really polarizing financing possibility for eCommerce companies are bank cards. They’re handy, versatile, and may normally be secured in just a few days or perhaps weeks.
Along with the financing advantages, many bank cards additionally supply rewards that may present enterprise homeowners with priceless perks, resembling money again and journey rewards.
Bank cards additionally give you a chance to delay fee utilizing their grace interval often known as the float.
Favourite Credit score Playing cards from the ECommerce Gas Neighborhood
There are just a few bank cards the ECF neighborhood loves.
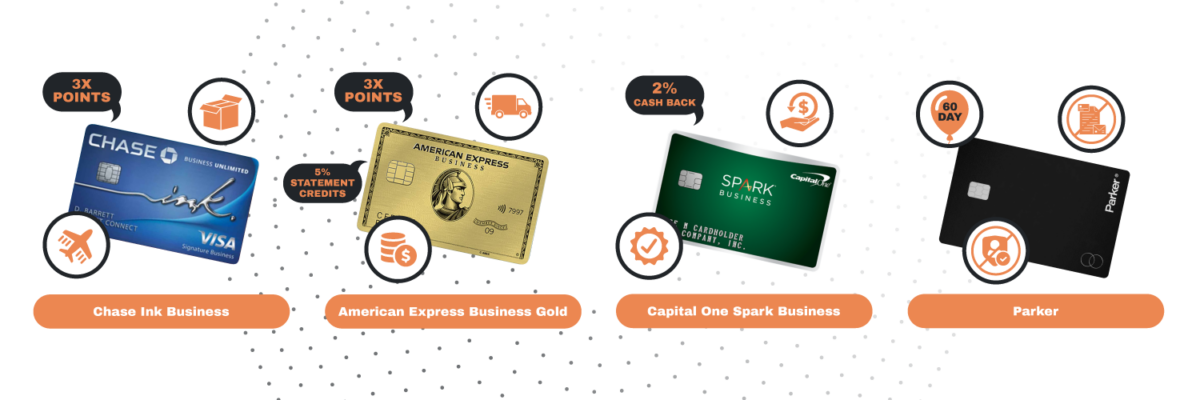
Chase Ink Enterprise: 3x factors for each buy spent on journey and delivery
American Specific Enterprise Gold: 3x factors on a single class of your selection. Enroll in FedEx open financial savings for five% assertion credit on FedEx fees
Capital One Spark Enterprise: Straightforward immediate approvals and flat 2% money again on every part
Parker: No collateral, no private assure, 60 day float
Some bank card charges from ECF members:
| Title | Fee | Restrict |
| Financial institution of America Enterprise Card | 13% APR | 70k |
| Chase Ink Most well-liked | 45k | |
| Capital One Spark Enterprise | 65k |
Credit score Card Rewards Wizardry
As somebody who doesn’t play the bank card recreation I can solely name it what it appears prefer to me: wizardry. ????
Whenever you get good at maximizing bank cards you will get some severe rewards. One dialogue on the ECF Discussion board was about combining the rewards from two Amex playing cards:
For those who spend $50k a month on delivery and promoting on an Amex Gold Card, due to the 4x multiplier with the NEW gold playing cards that’s 200k factors monthly.
You may switch Amex factors to Schwab with [Amex Platinum Charles Schwab] card the place every level is became $0.0125. Out of your Schwab account you may clearly money this out or use it to speculate.
If I spend $50k to get 200k factors and I switch these factors into Schwab, I get $2500 (200,000 x .0125). $2500 / $50,000 is 5%. So, primarily, I’m getting a 5% money rebate on my delivery and promoting spend.
With out this wizardry you possibly can get a 2% money again return with the Capital One Spark Enterprise card. However by utilizing slightly savvy and planning you will get a 5% money again return. Whenever you’re spending tens of hundreds on delivery and promoting that may be a big distinction.
Enterprise Credit score Card Protections
It will be significant for enterprise homeowners to remember that enterprise bank cards are usually not protected by the Credit score Card Act. The Credit score Card Act is a federal regulation that gives protections to customers. These protections do not apply to enterprise bank cards so purchaser beware.
Low Credit score Rating / New Enterprise Choices
ECommerce enterprise homeowners with low credit score scores or very new corporations might have issue accessing conventional types of financing, like financial institution loans. So let’s discover the choice financing choices for these sorts of eCommerce companies.
Crowdfunding
Crowdfunding platforms, like Kickstarter or Indiegogo permit companies to lift funds from a lot of particular person traders. It is a nice possibility if in case you have a brand new product that you simply wish to launch. You may safe the funding upfront to make merchandise for precisely the individuals who need them.
Enterprise Grants
Grants are financial awards from personal organizations or authorities entities. They don’t include monetary strings – which suggests you received’t should pay curiosity.
Nonetheless, the applying course of will be prolonged and really aggressive. Additionally, you will should do a major quantity of analysis to seek out grants your particular enterprise kind is certified for.
However there are definitely grant choices for eCommerce enterprise. For instance, the Enterprise Growth Financial institution of Canada is giving $15,000 to digitize your enterprise. And also you additionally get entry to a $100,000 mortgage with 0% curiosity. This might be a significant boon if your enterprise meets all the standards.
Service provider Money Advances & Income Primarily based Financing
Service provider money advances present companies a lump sum of money in trade for a share of future gross sales. This is usually a good possibility for eCommerce companies which have a gradual stream of incoming gross sales and wish entry to money shortly.
When you begin making gross sales, platforms like Amazon, PayPal, Shopify, or Wayflyer make it straightforward to request funding to develop your enterprise. Nonetheless, these charges are structured otherwise from the normal annual share fee (APR) you get from a bank card or financial institution mortgage.
For those who’re not cautious, service provider money advances can eat up a major quantity of your income.
One ECF discussion board consumer posted about their expertise with a service provider money advance:
We have now an impressive mortgage with Wayflyer now. We predict they’re pretty first rate. Not as low cost as a financial institution, however we’re paying shut to twenty% curiosity when adjusted for APR.
A frequent visitor on the ECF Podcast, Invoice D’Alessandro, shared a calculator that reveals how a 9% fixed-fee mortgage seems to be a 44% APR.
And right here is one other consumer’s sincere opinion of their service provider money advance:
The cash was wanted, I used to be grateful it was accessible, however holy crap the curiosity nearly ate us alive and stored us within the money crunch method longer than we wanted to be in it.
Attempt to finance your organization’s progress with conventional financing choices. However if you happen to’re nonetheless quick and wish money stream to keep up momentum, then a service provider money advance is perhaps your only option.
On-line Lending
It’s value mentioning that some on-line banks sit between a service provider money advance and a time period mortgage from a neighborhood brick and mortar financial institution. Two such examples are On Deck and Kabbage.
The charges are advanced and tough to check towards a standard APR fee. However usually they’re simpler to safe than a time period mortgage from a financial institution and cheaper than a service provider money advance.
Ultimate Ideas on Financing Your Enterprise
You desire a rising, thriving eCommerce enterprise. However progress usually comes with an elevated want for money. Whether or not you’re investing in a prolonged software and assessment course of for low rates of interest, or choosing quick money with increased rates of interest, ensure you make your best option on your firm’s wants – and continue to grow!
In order for you extra suggestions and assets to assist develop your eCommerce enterprise, be a part of our neighborhood of 7-8-figure model homeowners. All our members are vetted practitioners – not distributors or newcomers – guaranteeing everybody has a deep, significant eCommerce expertise to share. Sound fascinating? Apply for membership and be a part of us right this moment.
Publish by Patrick Rauland
Patrick loves entrepreneurship and teaches eCommerce, advertising, and WordPress programs at LinkedIn Studying. He is additionally developed each eCommerce and membership software program. When he isn’t in entrance of a display he loves to color tiny toy miniatures.
[ad_2]

