


[ad_1]
Fintech is booming. The world cryptocurrency market reached a worth of practically $1.8 trillion in 2021 and is projected to surpass $32 trillion by 2027. Neobanking can be on the rise: In 2020 the share of banking prospects utilizing a neobank or online-only financial institution was 23 % worldwide.
As fintech merchandise develop in recognition, designers who perceive finance and know learn how to shield customers’ helpful belongings can be in demand. Designers can’t cease folks from making unhealthy monetary choices, however with regards to fintech merchandise, designers can reduce usability points and defend customers from errors which will result in monetary hurt.
For fintech, consumer analysis is crucial: No person desires customers to overlook paying a invoice or by chance authorize a transaction as a result of they’re confused about what a button does. However for a lot of fintech merchandise, analysis alone just isn’t sufficient to fulfill consumer and enterprise wants. Finance is just too complicated to select up by means of interviews and contextual inquiry—you should perceive the mechanics with the intention to remedy complicated fintech design issues and accomplice successfully along with your workforce.
Finance 101: Get Began
Fintech is an umbrella time period for monetary expertise that encompasses client banking apps, complicated back-end information evaluation engines, and all the pieces in between. For the needs of this text, I’m going to deal with investing and three areas I’ve labored in myself: overseas alternate (foreign exchange), cryptocurrency, and neobanks.
For those who don’t know the place to begin with these subjects, Investopedia is a complete clearinghouse of knowledge on private finance, cryptocurrency, and extra. Moreover, many monetary publications have free newsletters. The Wall Avenue Journal, The Economist, the Monetary Instances, Barron’s, Bloomberg, MarketWatch, CNBC, and Axios are common within the English-speaking world.
Nonetheless, to actually comprehend finance and fintech, you could undertake additional examine. Listed here are my advisable beginning factors for frequent kinds of fintech and key monetary subjects:
Investing
Most on-line funding platforms are designed for purchasing and promoting securities comparable to shares and bonds by means of a dealer on the inventory market such because the New York Inventory Alternate. Customers of those platforms embrace these making occasional investments for school or retirement and day merchants who make their residing from it.
Study extra:

Foreign exchange
Foreign exchange includes shopping for and promoting overseas forex to make a revenue. The foreign exchange market is the largest capital market on the earth. There are not any centralized markets for foreign currency trading as there are for securities, so enterprise hours don’t matter.
Study extra:
Cryptocurrency
Cryptocurrency is a brand new kind of asset that lives on the blockchain—a decentralized public ledger that’s just about inconceivable to forge or hack. There are dozens of cryptocurrencies accessible right now, although the most well-liked ones are bitcoin and ethereum. Customers purchase and promote crypto on non-public exchanges and retailer it in digital “wallets.”
Study extra:
Neobanks
Neobanks, generally known as challenger banks, are online-only. They usually supply a extra restricted vary of companies—comparable to primary checking, financial savings accounts, and ATM playing cards—and have a tendency to have a lot decrease charges than conventional banks, or none in any respect. Neobanks’ main worth proposition, after value, is ease of use.
Study extra:

Cross-border and Interbank Funds
Transferring funds between banks, notably internationally, is a posh course of that depends on an interbank switch system to route the funds by means of middleman banks to be processed. For worldwide funds, there’s an added layer of forex alternate. Probably the most outstanding such system is the worldwide SWIFT system, however there are others, together with the Eurozone’s SEPA. Nationwide interbank fee techniques embrace US’s ACH, the UK’s Sooner Funds, and Singapore’s FAST.
Study extra:
Monetary Laws
Any designer engaged on a fintech product ought to regularly seek the advice of with authorized counsel, but it surely’s nonetheless a good suggestion to have a grasp of frequent finance rules. For instance, understanding anti-money-laundering guidelines—which require sure fintech customers to supply in depth documentation of their id—will allow you to design consumer onboarding flows that fulfill authorized necessities whereas minimizing consumer frustration. You also needs to perceive your authorities’s deposit insurance coverage program and related tax legal guidelines so that you embrace acceptable warnings and disclosures.
Study extra: Each nation has its personal legal guidelines and guidelines. Authorities web sites are probably the most authoritative, however not all the time probably the most user-friendly. For those who need assistance discovering a good useful resource, contact your native library.
Fintech UX/UI Undertaking Wants
Whereas each mission is exclusive, fintech UX designers will encounter some frequent challenges.
Please notice: I’m sharing these insights that will help you perceive the problems that you just’ll must assume by means of—to not let you know one of the best ways to unravel a selected design downside. Work along with your workforce’s finance and authorized consultants to make sure that your designs adjust to all legal guidelines and rules.
Onboarding
The regulation requires most monetary companies suppliers to confirm customers’ identities by having them fill out in depth know-your-customer varieties. Doing so prevents id theft, tax evasion, and cash laundering. Some apps additionally make the consumer scan their official ID and take a video selfie whereas performing a particular process, comparable to turning their head or reciting a sequence of numbers, to show that the photograph within the ID belongs to the particular person opening the account. This verification is essential within the age of photograph enhancing and deepfakes.
To cut back the interplay value of this course of, notably on cell phones, it’s finest to ask as few questions as potential. Work intently along with your workforce’s authorized counsel, because the authorized necessities differ. For a crypto buying and selling app, a consumer could also be permitted to ascertain an account with minimal data (although they might be required to supply extra data once they’re prepared to begin buying and selling). For a neobank, nonetheless, the consumer might have to supply all their data upfront.
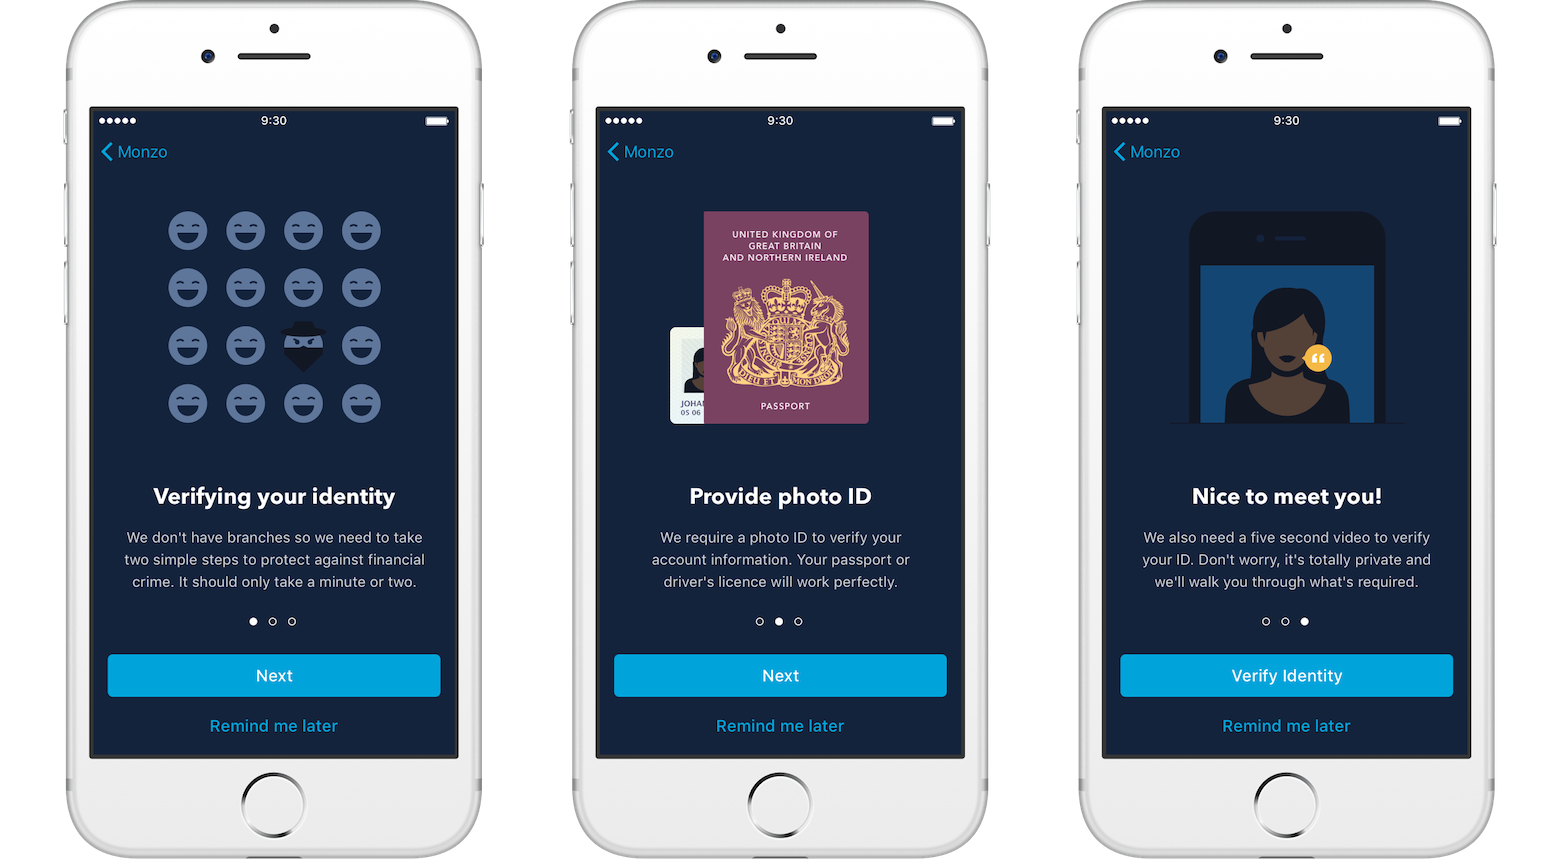
If the consumer should full an extended questionnaire, I preserve it to about 5 questions per display to make sure it feels manageable. I additionally attempt to reduce the quantity of typing required by offering drop-downs for standardized responses. Nonetheless, for authorized causes, it’s essential to not push customers to decide on solutions which can be unfaithful or “shut sufficient.” For instance, if customers are required to share their earnings, you’ll get extra correct outcomes for those who ask them to kind within the precise quantity slightly than select from a listing of ranges.
Take a look at these flows rigorously to optimize them. If one thing goes improper throughout onboarding, the consumer is prone to change into pissed off or lose belief within the product and take their enterprise elsewhere.
Deposits and Transfers
It’s troublesome to design flows for on-line deposits and transfers with out understanding how interbank transfers work. The consumer wants to gather and precisely enter quite a lot of data, together with account numbers, to make sure a profitable switch. Growing a consumer circulation that minimizes errors is essential. One method to shield the consumer from making an error is to require a “penny check” for the primary deposit, which includes sending a really small amount of cash to the recipient account to substantiate that each one the routing data is appropriate. Solely then can the consumer ship the total quantity.

Worldwide transfers are much more complicated. Relying on what nation you’re in, you might not be allowed to ship cash to or obtain cash from sure nations. There could also be limits on how a lot cash you may switch, and customers in sure nations might not be allowed to make worldwide transfers. All of those concerns should be constructed into your design so that you don’t by chance allow a consumer to do one thing unlawful.
Commerce Orders
Buying and selling shares, cryptocurrency, and overseas forex is drastically completely different than making an e-commerce buy. The value of those belongings fluctuates consistently throughout buying and selling hours, so the worth might change mid-transaction, leaving you with roughly than you meant to purchase. Charges may also differ. Fintech firms account for this in several methods—some will freeze the fee for the consumer after which take in the distinction, whereas others don’t. In these circumstances, the consumer should be made conscious that their buy value is approximate.

Total Look and Really feel
For fintech apps—particularly for desktop merchandise meant for extended use—a fastidiously thought-about darkish mode palette doesn’t simply look cool; it’s important to well-being. A day dealer might be 4 displays directly all day lengthy, and most discover darkish mode is less complicated on the eyes. To design a nice darkish UI, you may’t simply design in gentle mode first, then invert onto a darkish grey background. For instance, darkish mode usually requires less-saturated variations of the colours you utilize in gentle mode.

Whereas banking apps are likely to have extra conventional UIs, buying and selling terminals have their very own guidelines. For instance, it’s commonplace to see dozens of columns of numbers rendered in eight-point fonts with the intention to pack as a lot element onto the display as potential. That’s not an accident—monetary execs should take note of and react to an infinite quantity of knowledge that modifications shortly, and the extra that’s accessible in a single look, the higher.
Remember that it’s going to be troublesome to seek out customers who will check your product for a full, eight-hour workday, so be considerate and cautious with these designs.
Able to Begin?
In case you are able to dive into the world of fintech, I like to recommend beginning with a banking app as a result of their transactions are extra simple than crypto or foreign exchange trades. Plus, their UX will more than likely be acquainted to you, and their UI will comply with finest practices which can be much like e-commerce websites.
When you’re dedicated to a profession in fintech design, I like to recommend opening an actual account or two and executing some trades of your personal. This can put you in your consumer’s sneakers higher than the rest can. (After all, solely do that for those who can afford to, and ensure you perceive the dangers and tax implications earlier than you begin.)
A vital piece of recommendation: By no means take a fintech job that doesn’t have a lawyer or a monetary knowledgeable on the workforce. Even when your contract protects you from authorized legal responsibility, it’s nonetheless a horrible feeling to comprehend your work might have harmed somebody.
The world of finance is fascinating, and so is the problem of designing fintech UX. Gaining the competencies you could do it properly will take some effort, but when these ideas excite you, the outcomes are value it.
[ad_2]

