


[ad_1]
Final yr, our report on cloud adoption confirmed that firms had been transferring shortly to undertake the cloud: 88% of our respondents from January 2020 stated that they used the cloud, and about 25% stated that their firms deliberate to maneuver all of their functions to the cloud within the coming yr.
This yr, we needed to see whether or not that pattern continued, so we ran one other on-line survey from July 26, 2021, to August 4, 2021. Because the 2020 survey was taken when the pandemic was looming however hadn’t but taken maintain, we had been additionally interested by how the lockdown affected cloud adoption. The brief reply is “not a lot”; we noticed surprisingly few adjustments between January 2020 and July 2021. Cloud adoption was continuing quickly; that’s nonetheless the case.
Study sooner. Dig deeper. See farther.
Government abstract
- Roughly 90% of the respondents indicated that their organizations are utilizing the cloud. That’s a small improve over final yr’s 88%.
- The response to the survey was international; all continents (save Antarctica) had been represented. In comparison with final yr, there was a a lot greater share of respondents from Europe (33%, versus 11%) and a decrease share from North America (42%).
- In each business, a minimum of 75% of the respondents work for organizations utilizing the cloud. Probably the most proactive industries are retail & ecommerce, finance & banking, and software program.
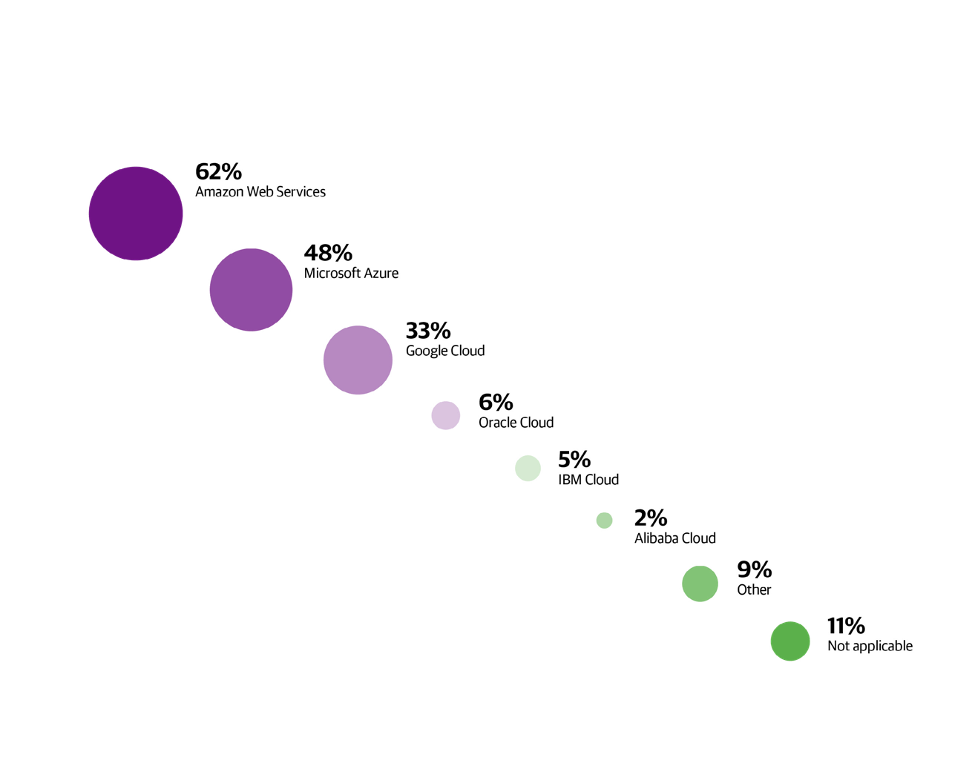
- Amazon Net Companies (AWS) (62%), Microsoft Azure (48%), and Google Cloud (33%) are nonetheless the large three, although Amazon’s market share has dropped barely since final yr (down from 67%). Most respondents use a number of cloud suppliers.
- Trade to business, we noticed few variations in cloud suppliers, with two exceptions: Azure is used extra closely than AWS within the authorities and consulting & skilled companies sectors.
- Two-thirds of respondents (67%) reported utilizing a public cloud; 45% are utilizing a personal cloud; and 55% are utilizing historically managed on-premises infrastructure.
- Nearly half (48%) stated they plan emigrate 50% or extra of their functions to the cloud within the coming yr. 20% plan ti migrate all of their functions.
- 47% stated that their organizations are pursuing a cloud first technique. 30% stated that their organizations are already cloud native, and 37% stated that they plan to be cloud native inside three or extra years. Solely 5% are engaged in “repatriation” (bringing cloud functions again to on-premises infrastructure).
- Amongst respondents who’re utilizing the cloud, the most important concern is managing value (30%). Compliance is a comparatively minor concern (10%) and isn’t probably the most vital concern even in closely regulated sectors comparable to finance & banking (15%), authorities (19%), and healthcare (19%).
- When requested what expertise organizations wanted to succeed, respondents had been divided pretty evenly, with “cloud-based safety” (59%) and “common cloud information” (54%) the most typical responses.
Demographics: Who responded
The survey was despatched to recipients of O’Reilly’s Programming and Infrastructure & Ops Newsletters, which collectively have 436,000 subscribers. 2,834 respondents accomplished the survey.
The respondents symbolize a comparatively senior group. 36% have over 10 years’ expertise of their present position, and virtually half (49%) have over seven years’ expertise. Newer builders had been additionally well-represented. 23% have spent one to a few years of their present place, and eight% have spent underneath one yr.
Parsing job titles is at all times problematic, provided that the identical place may be expressed in many various methods. However, the highest 5 job titles had been developer (4.9%1), software program engineer (3.9%), CTO (3.0%), software program developer (3.0%), and architect (2.3%). We had been shocked by the variety of respondents who had the title CTO or CEO. No one listed CDO or chief knowledge officer as a title.
Aggregating phrases like “software program,” “developer,” “programmer,” and others lets us estimate that 36% of the respondents are programmers. 21% are architects or technical leads. 10% are C-suite executives or administrators. 8% are managers. Solely 7% are knowledge professionals (analysts, knowledge scientists, or statisticians), and solely 6% are operations employees (DevOps practitioners, sysadmins, or web site reliability engineers).
The respondents got here from 128 totally different nations and had been unfold throughout all continents aside from Antarctica. A lot of the respondents had been from North America (42%) and Europe (33%). 13% had been from Asia, although that nearly definitely doesn’t mirror the extent of cloud computing in Asia.
Particularly, there have been few respondents from China: solely 8, or about 0.3% of the full. South America, Oceania, and Africa had been additionally represented, by 6%, 4%, and a pair of% of the respondents, respectively. These outcomes are considerably totally different from final yr’s. In 2020, two-thirds of the respondents had been from North America, and solely 11% had been from Europe. The opposite continents confirmed little change. Final yr, we famous that European organizations had been reluctant to undertake the cloud. That’s clearly not true.
Cloud customers are unfold all through the economic spectrum. Respondents to our survey had been clustered most strongly within the software program business (36%). The subsequent largest group contains these who replied “different” (13%), and they’re certainly scattered by industries from artwork to aviation (together with some outliers like prophecy, which we by no means knew was an business). Consulting & skilled companies (12%) was third; we suspect that many respondents on this group might equally effectively say they had been in the software program business. Finance & banking (11%) was additionally well- represented. 5% of the respondents work in healthcare; one other 5% had been from greater schooling; 4% had been in authorities; and a complete of 4% work in electronics & {hardware} or computer systems (2% every). Surprisingly, solely 3% of the respondents work in retail & ecommerce; we’d have anticipated Amazon alone to account for that.
These outcomes are similar to the outcomes from final yr’s survey, with two main variations: this yr, a fair bigger share of our respondents had been from the software program business (23% in 2020), and a considerably bigger group labeled their industries as “different” (20%).
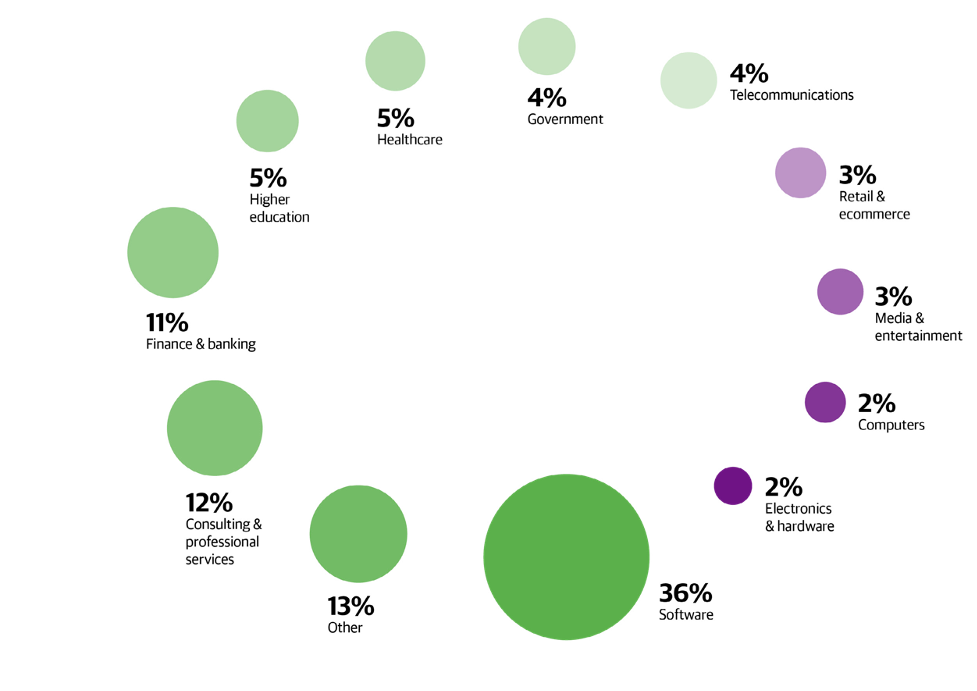
What does this imply? Lower than it appears. We have now to remind each ourselves and our readers that the variety of respondents in any sector displays, first, the dimensions of that sector; second, our mailing lists’ penetration into that sector; and solely third, cloud utilization in that sector. The truth that 35% of the respondents are within the software program business whereas solely 5% are in healthcare doesn’t by itself imply that the cloud has penetrated rather more deeply into software program. It signifies that the healthcare business has fewer readers of our newsletters than does the software program business, hardly a stunning conclusion. To estimate cloud utilization in any given sector, you need to look solely at that sector’s knowledge. What it says is that our conclusions concerning the software program business are based mostly on roughly 1,000 respondents, whereas conclusions concerning the healthcare business are solely based mostly on about 150 respondents, and are correspondingly much less dependable.
The massive image
The massive image gained’t shock anybody. Nearly the entire respondents work for organizations which can be utilizing cloud computing; solely 10.3% answered a query asking why their group doesn’t use cloud computing, implying that cloud utilization is 89.7%. Likewise, when requested what cloud supplier they’re utilizing, 10.7% stated “not relevant,” suggesting cloud utilization of 89.3%. We are able to get a 3rd repair on cloud utilization by taking a look at a later query about cloud applied sciences. We requested whether or not respondents are utilizing public clouds, non-public clouds, hybrid clouds, multiclouds, or historically managed
infrastructure. Respondents had been allowed to pick out a number of solutions, and most did. Nevertheless, respondents whose organizations aren’t utilizing any cloud expertise would test “historically managed infrastructure.” These respondents amounted to 7.5% of the full, suggesting 92.5% of the respondents are utilizing the cloud in some type. Subsequently, we will say with some confidence that the variety of respondents whose organizations are utilizing the cloud is someplace between 89% and 93%.
These figures examine with 88% from our 2020 survey—a change that could be insignificant. Nevertheless, it’s price asking what “insignificant” means: would we count on the variety of “not utilizing” responses to be close to zero? On one hand, we’re shocked that there hasn’t been a bigger change from yr to yr; then again, once you’re already close to 90%, gaining even a single share level is tough. We may be considerably (solely considerably) assured that there’s a real pattern as a result of we requested the identical query three alternative ways and bought comparable outcomes. A further share level or two could also be all we get, even when it doesn’t permit us to be as assured as we’d like.
Did the pandemic have an impact? It definitely didn’t sluggish cloud adoption. Cloud computing was an apparent resolution when it grew to become tough or unimaginable to employees on-premises infrastructure. You can argue that the pandemic wasn’t a lot of an accelerant both, and it might be arduous to disagree. As soon as once more although, once you’re at 88%, gaining a share level (or two or three) is an achievement.
AWS, Azure, and Google Cloud: The massive three and past
The massive three in cloud computing are Amazon Net Companies (AWS), Microsoft Azure, and Google Cloud, utilized by 62%, 48%, and 33% of the respondents, respectively. (As a result of many organizations use a number of suppliers, respondents had been allowed to pick out a couple of possibility.) Oracle Cloud (6%), IBM Cloud (5%), and Alibaba Cloud (2%) took fourth by sixth place. They’ve a protracted solution to go to catch as much as the leaders,
though Oracle appears to have surpassed IBM. It’s additionally price noting that, though Alibaba’s 2% appears weak, we count on Alibaba to be strongest in China, the place we had only a few respondents. Higher visibility into Chinese language business may change the image dramatically.
9% of the respondents chosen “different” as their cloud supplier. The main “different” supplier was Digital Ocean (1.4%), which nearly edged out Alibaba. Salesforce, Rackspace, SAP, and VMware additionally appeared among the many “others,” together with the Asian supplier Tencent. Many of those “different” suppliers are software-as-a-service firms that don’t present the sort of infrastructure companies on which the large three have constructed their companies. Lastly, 11% of the respondents answered “not relevant.” These are presumably respondents whose organizations aren’t utilizing the cloud.
In comparison with final yr, AWS seems to have misplaced some market share, going from 67% in 2020 to 62%. Microsoft Azure and Google Cloud stay unchanged.
Cloud utilization by business
One purpose of our survey was to find out how cloud utilization varies from business to business. We felt that one of the simplest ways to reply that query was to go at it in reverse, by trying on the respondents who answered the query “What finest describes why your group doesn’t use cloud computing?” (which we’ll talk about in additional element later). Our outcomes offered different methods to reply this query—for instance, by taking a look at “not relevant” responses to questions on cloud suppliers. All approaches yielded considerably the identical solutions.
We discovered that retail & ecommerce, media & leisure, finance & banking, and software program stand out because the business sectors with the very best cloud use. Solely 3.1% of the respondents from the retail & ecommerce sector answered this query, indicating that cloud utilization was near common (96.9%). 5.1% of the respondents in media & leisure, 7.2% of the respondents in finance & banking, and seven.5% of the respondents in software program answered this query, suggesting 94.9%, 92.8%, and 92.5% cloud utilization, respectively. Most industries (together with healthcare and better schooling) clustered round 10% of organizations that aren’t utilizing the cloud, or 90% cloud utilization. Probably the most cloud-averse industries had been electronics & {hardware} (with 25% indicating that they don’t use the cloud) and authorities (16% not utilizing). However think about: 25% of respondents indicating that they don’t use the cloud implies that 75% of the respondents do. Whereas we noticed variation from business to business, cloud customers are a stable majority all over the place.
Can we get past the numbers to the “why”? Maybe not with out a way more detailed survey, however we will make some guesses. Though we had few respondents from the retail & ecommerce sector, it’s necessary to notice that this business is the place the cloud took off: AWS started when Amazon began promoting “extra capability” in its knowledge facilities. Jeff Bezos paved the best way for this along with his well-known “API mandate” memo, which required all software program to be constructed as collections of companies. In media & leisure, Netflix has been very public about its cloud technique. The corporate depends on the cloud for all of its scalable computing and storage wants, an strategy initially undertaken as a manner of avoiding on-premises infrastructure as a single level of failure.
However historical past typically counts for little in tech. What’s extra necessary is that retail & ecommerce is a sector topic to very large fluctuations in load. Black Friday is approaching as we publish this; want we are saying extra? In case your ecommerce web site slows to a crawl underneath heavy load, you lose gross sales. The cloud is a perfect resolution to that drawback. No CIO desires to construct an on-premises knowledge middle that may deal with 100x adjustments in load. The identical is true for Netflix, although maybe to not the identical diploma: a brand new film launch virtually definitely creates a spike in visitors, probably an enormous one. And within the
previous few years, film studios, distributors like Amazon, and plenty of others within the business have realized that the way forward for motion pictures lies in promoting subscriptions to streaming companies, not cinema tickets. Cloud applied sciences are perfect for streaming companies.
Nearly each software program firm, from startups to established distributors like Microsoft and Adobe, now gives “software program as a service” (SaaS), an strategy arguably pioneered by Salesforce. Whether or not or not subscription companies are the way forward for software program, most software program firms are betting closely on cloud choices, and so they’re constructing these choices within the cloud.
Understanding why banks are transferring to the cloud could also be tougher, however we predict it comes right down to focusing in your core competence. The finance & banking business has traditionally been very conservative, with organizations going for many years with out vital change to their enterprise fashions or procedures. Up to now decade, that stability has gone out the window. Monetary service firms and banks are actually providing on-line and cellular merchandise, funding companies, monetary planning, and rather more. One of the simplest ways to service these new functions isn’t by constructing out legacy infrastructure designed to assist legacy functions largely unchanged because the starting of computing; it’s by transferring to an infrastructure that may scale on demand and that may be shortly tailored to assist new functions.
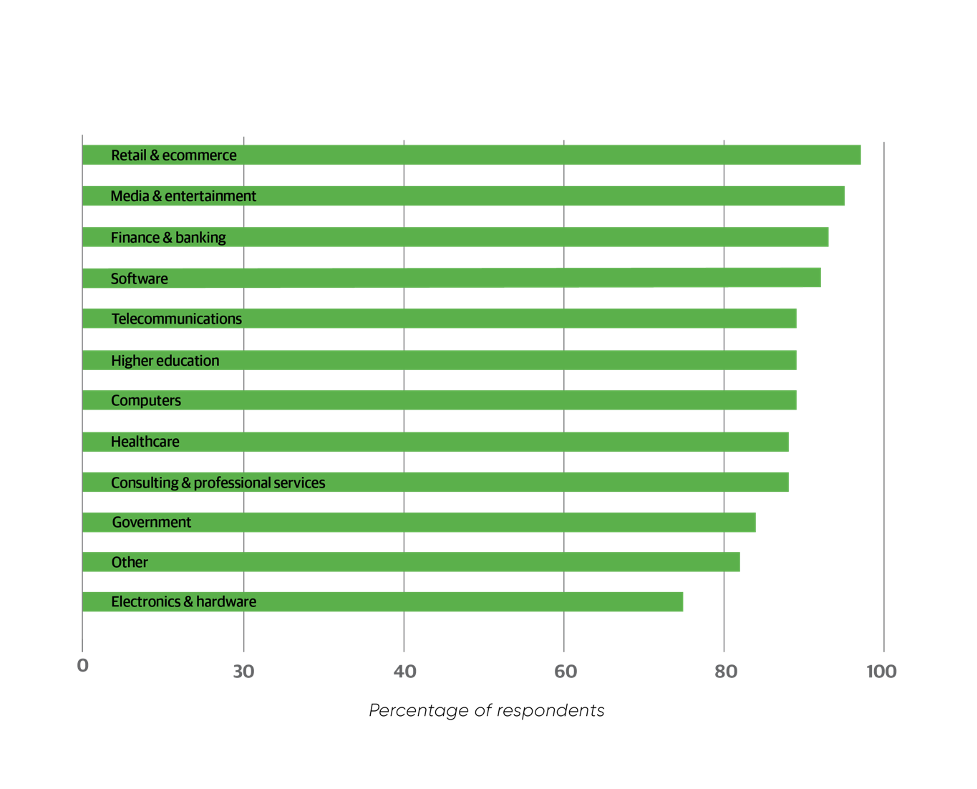
Our subsequent step was to take a look at the cloud suppliers to find out what suppliers are utilized by every business. Are some suppliers used extra extensively in sure industries than in others? Once we checked out this query, we noticed a well-known sample: AWS is probably the most extensively used, adopted by Microsoft Azure and Google Cloud. AWS dominates media & leisure (79%) and is probably the most generally used supplier in each sector aside from consulting & skilled companies (58%, in comparison with Azure at 60%) and authorities (52%, in comparison with Azure at 59%).
Along with authorities and consulting & skilled companies, Azure is extensively utilized in finance & banking (55%). That shouldn’t be stunning given the historic prominence of Microsoft Workplace on this business.
Google Cloud was third in each sector aside from media & leisure (35%), the place it edged out Azure. It’s strongest within the consulting & skilled companies sector (41%) and the comparatively small computer systems sector (40%) and weakest in authorities (16%), healthcare (25%), and finance & banking (29%).
Electronics & {hardware} had the best variety of respondents who answered “not relevant” (28%). Though there have been surprisingly few respondents from the retail & ecommerce sector, it had the fewest (3%) respondents who answered “not relevant.”
AWS’s, Microsoft Azure’s, and Google Cloud’s shares had been closest to one another within the greater schooling sector (49%, 43%, and 39%, respectively).

Cloud utilization by geography
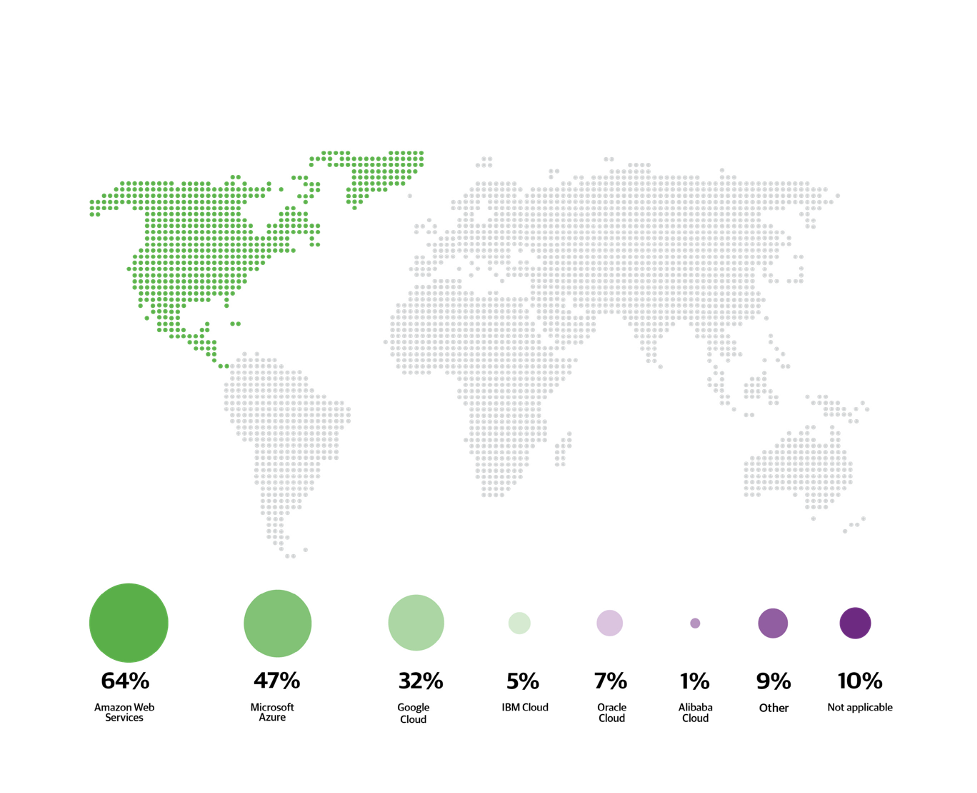
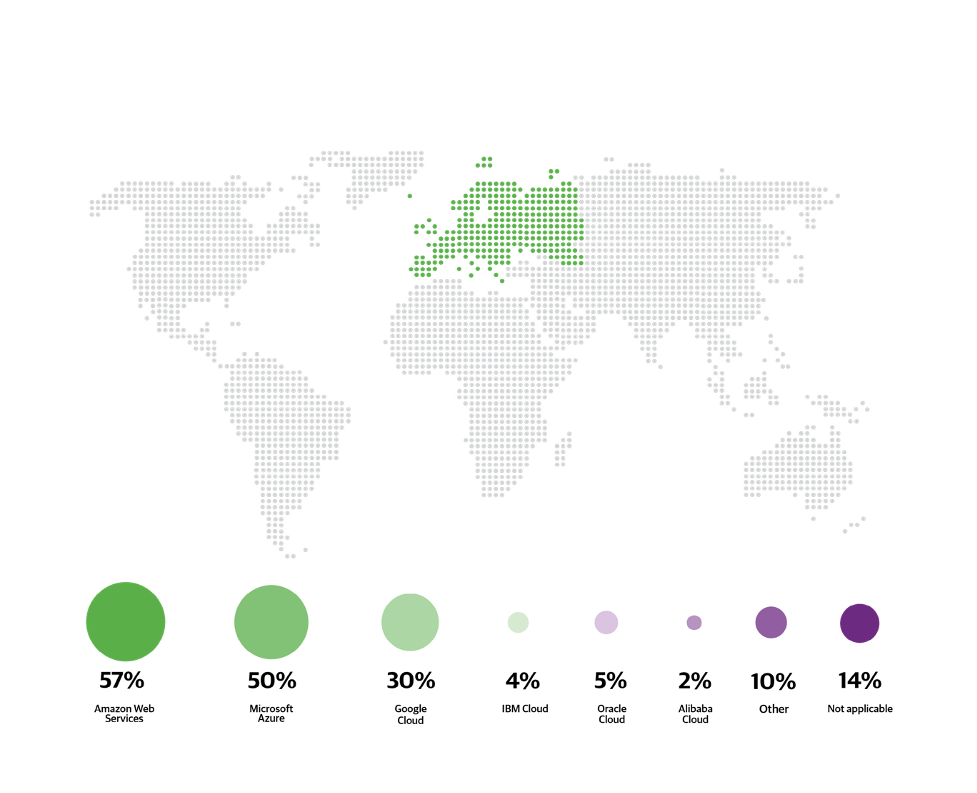
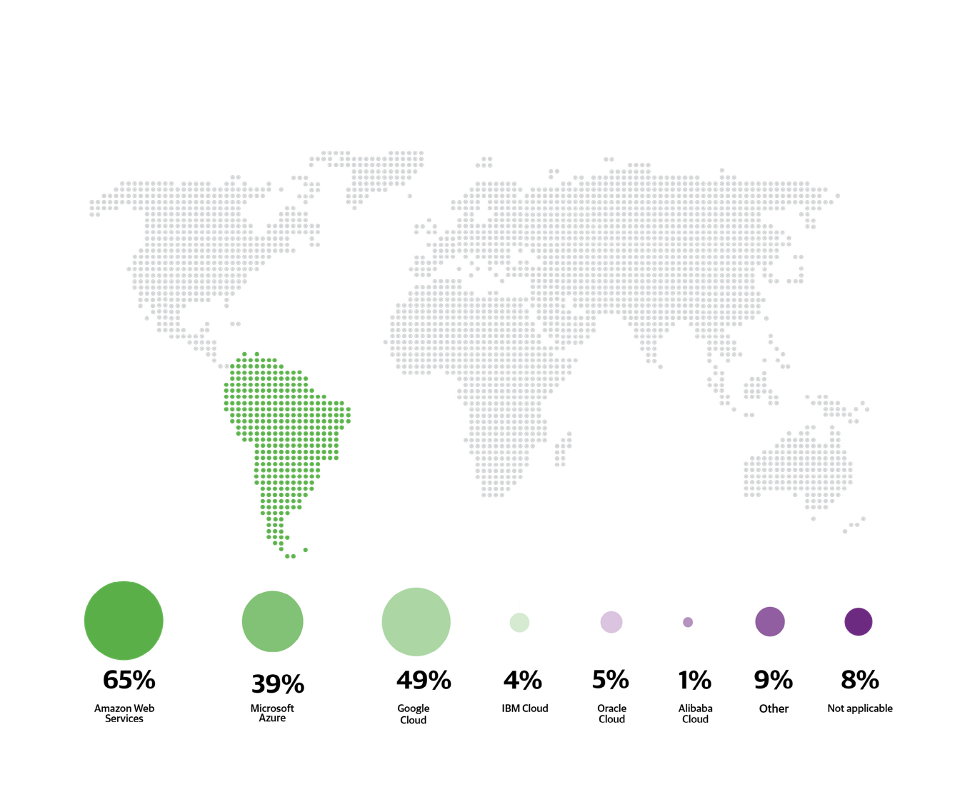
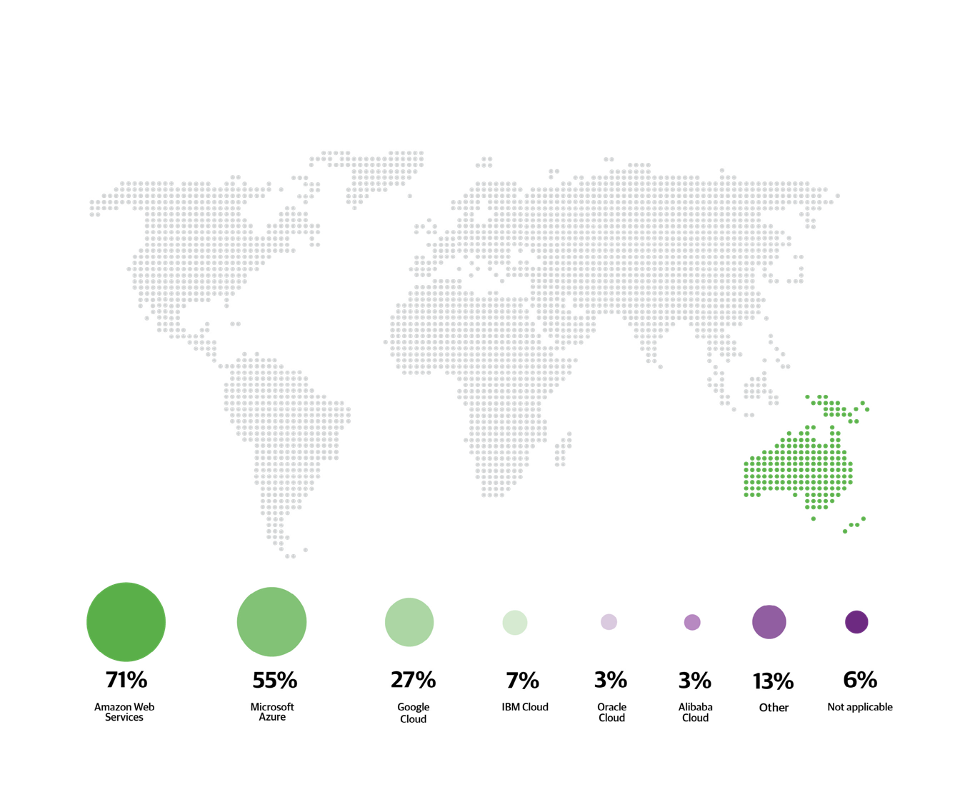
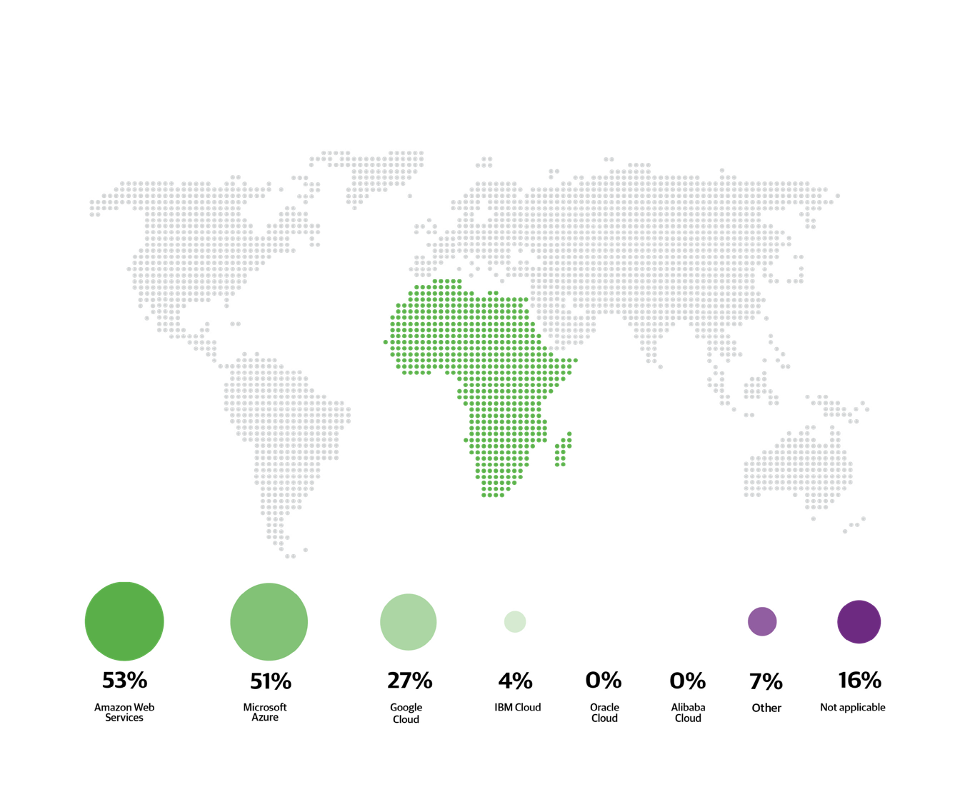
We questioned whether or not the utilization of various cloud suppliers diversified by continent: are some cloud suppliers extra widespread on some continents than on others? By and enormous, the reply isn’t any. AWS leads by a considerable margin on each continent, and Microsoft Azure and Google Cloud take second and third place, although their relative strengths differ. Google Cloud is considerably stronger in South America (49%) and Asia (40%) than on the opposite continents. Azure is strongest in Oceania (55%), Africa (51%), and Europe (50%).
Alibaba Cloud is a considerably extra frequent alternative in Asia (5%) and Oceania (3%), however not sufficient to vary the image considerably. Keep in mind, although, that we had few respondents from China, the place we suspect that cloud adoption is important and Alibaba is a powerful contender.
Though the odds are comparatively small, it’s additionally price noting that extra respondents in Oceania are utilizing “different” suppliers (13%), probably as a result of their relative geographic isolation makes native cloud suppliers extra engaging, and that a big share of respondents in Europe answered “not relevant” (14%), indicating that cloud adoption should be lagging considerably.
North America
Europe

Asia
South America
Oceania
Africa
Whereas we’ll talk about multicloud in additional element later, it’s attention-grabbing that this diagram offers some hints concerning the extent of deployment on a number of clouds. Keep in mind that respondents might and regularly did choose a number of cloud suppliers, so the full share in any continent (at all times higher than 100%) is a really tough indicator of a number of cloud deployments. By that measure, Africa (totaling 142%) and Europe (158%) have the fewest a number of cloud deployments; Oceania (179%) has probably the most.
Public or not
We requested our respondents what cloud applied sciences they’re utilizing. 67% (two-thirds) are utilizing a public cloud supplier, comparable to AWS, versus 61% in 2020. 45% are utilizing a personal cloud—non-public infrastructure (on-premises or maybe hosted) that’s accessed utilizing cloud APIs—which represents a ten% improve over 2020 (35%). And 55% are utilizing historically managed on-premises infrastructure, versus 49% final yr.
Respondents might choose a number of solutions, and plenty of did. It’s not stunning that so many organizations look like utilizing on-prem infrastructure; we’re really shocked that the quantity isn’t greater, since in any cloud transformation, the remnants of conventional infrastructure are essentially the very last thing to vanish. And most firms aren’t that far alongside of their transformations. Transferring to the cloud could also be an necessary purpose, and cloud sources are in all probability already offering crucial infrastructure. However eliminating all (and even most) conventional infrastructure is a really heavy elevate.
That’s not the entire story. 29% of the respondents stated they’re utilizing a hybrid cloud (a major drop from final yr’s 39%), and 23% are utilizing multicloud (roughly the identical yr over yr). A multicloud technique builds techniques that run throughout a number of cloud suppliers. Hybrid cloud goes even farther, incorporating non-public cloud infrastructure (on-premises or hosted) working cloud APIs. When performed appropriately, multiclouds and hybrid clouds can present continuity within the face of supplier outages, the flexibility to make use of “one of the best device for the job” on totally different software workloads (for instance, leveraging Google Cloud’s AI amenities), and simpler regulatory compliance (as a result of delicate workloads can keep on non-public techniques).
Subsequently, respondents who chosen “hybrid cloud” also needs to have chosen “public cloud” and “non-public cloud” (or, probably, “conventional infrastructure”). Certainly, that’s what we noticed. Solely 11% of the respondents who chosen “hybrid cloud” didn’t choose some other varieties—and we’d wager that’s as a result of they assumed that “hybrid” implied the others. 27% of those that chosen “hybrid” chosen all 5 varieties, and the rest chosen some mixture of the 5 choices. The identical was true for respondents who chosen “multicloud”: solely 4% chosen “multicloud” by itself. (“Multicloud” and “hybrid cloud” had been regularly chosen collectively.)
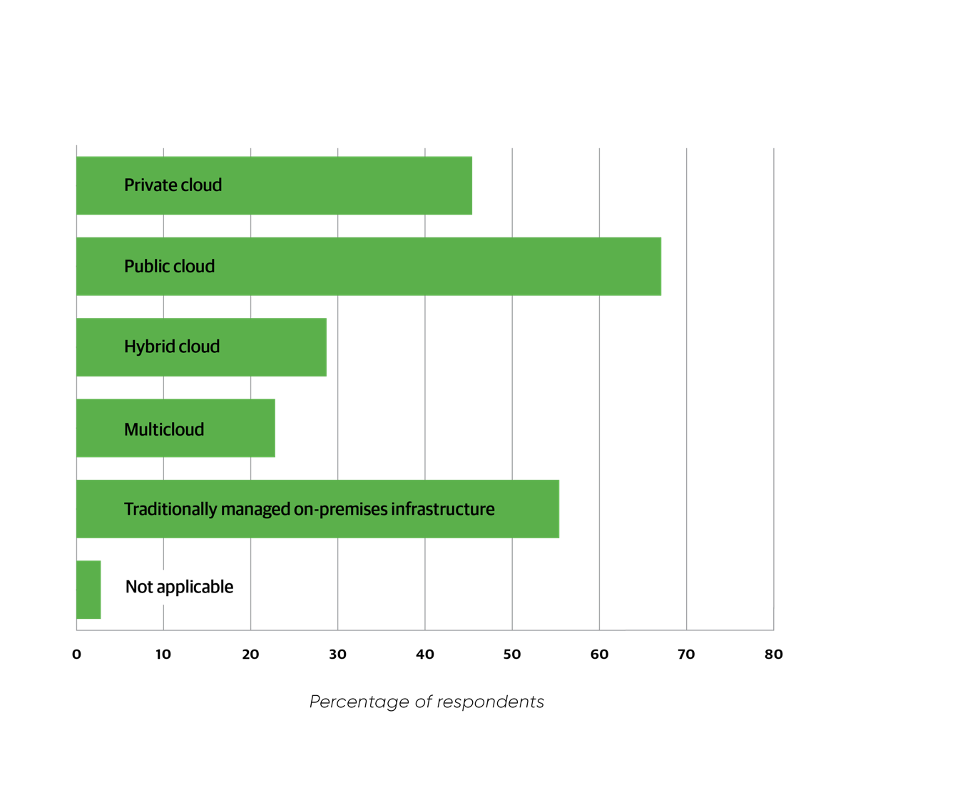
We’re puzzled by the distinction between 2020 and 2021. An improve in using public clouds, non-public clouds, and even conventional infrastructure is smart: customers have clearly develop into extra comfy mixing and matching infrastructure to swimsuit their wants. We don’t count on using conventional infrastructure to disappear. However why did utilization of hybrid clouds drop? We don’t have an excellent reply, besides to notice that many respondents (certainly, a 3rd of the full) who didn’t choose both “multicloud” or “hybrid cloud” nonetheless chosen a number of infrastructure varieties. A mix of public cloud and conventional infrastructure was most typical, adopted by public cloud, non-public cloud, and conventional infrastructure. These mixtures point out that many respondents are clearly utilizing some type of multicloud or hybrid cloud, even when they aren’t together with that of their responses.
We are able to’t ignore the slip within the share of respondents answering “hybrid cloud.” That will point out some skepticism about this most formidable cloud structure. It might even be an artifact of the pandemic. We’ve already stated that the pandemic gave many firms an excellent cause to maneuver on-premises infrastructure to the cloud. However whereas the pandemic might have been an excellent time to begin cloud transformations, it was arguably a poor time to begin very formidable initiatives. Can we think about CTOs saying, “Sure, we’re transferring to the cloud, however we’re conserving it so simple as doable” Positively.
We additionally checked out what forms of cloud applied sciences had been engaging to totally different industries. Public clouds are most closely utilized in retail & ecommerce (79%), media & leisure (73%), and software program (72%). Hybrid clouds are strongest in consulting & skilled companies (38%), probably as a result of consultants typically play a task in integrating totally different cloud suppliers right into a seamless entire.Non-public clouds are strongest in telecommunications (64%), which was the one sector by which non-public clouds led public clouds (60%).
Historically managed on-premises infrastructure is most generally utilized in authorities (72%). Different industries the place the variety of respondents utilizing conventional infrastructure equaled or exceeded the quantity reporting any type of cloud infrastructure included greater schooling (61%), healthcare (61%), telecommunications (67%), computer systems (65%), and electronics & {hardware} (58%).

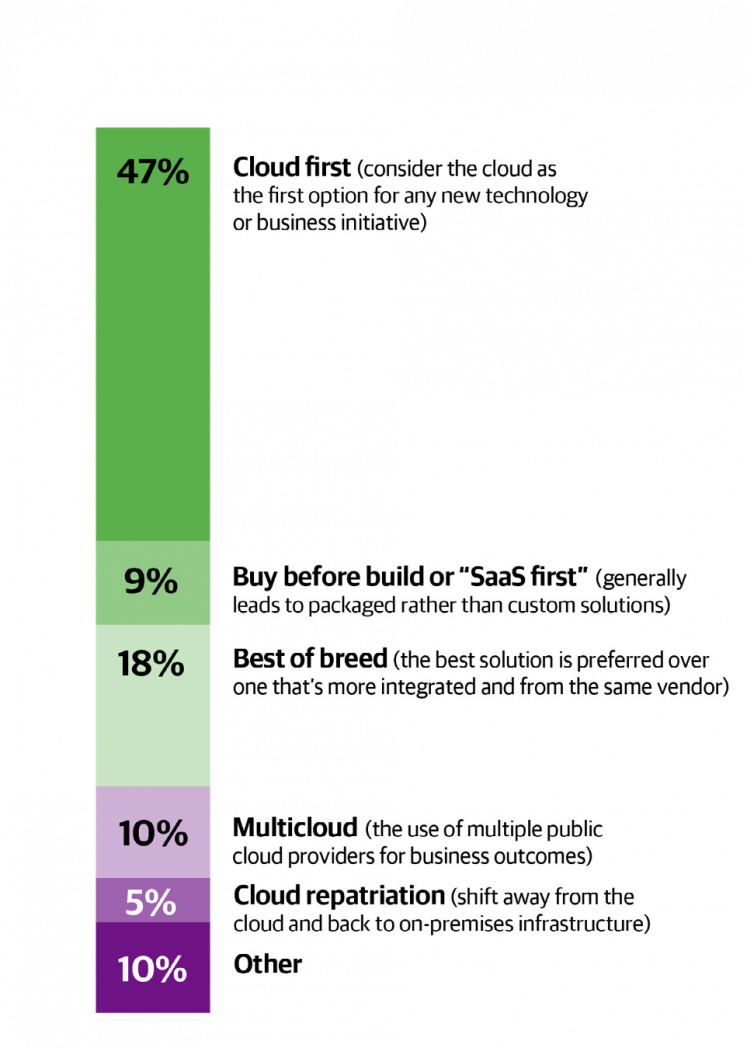
When requested about their group’s cloud technique, virtually half of the respondents (47%) answered “cloud first,” which means that wherever doable, new initiatives think about the cloud as the primary possibility. Solely 5% chosen “cloud repatriation,” or bringing companies that had been beforehand moved to the cloud again in-house. 10% indicated a multicloud technique, the place they work with a number of public cloud suppliers; and 9% indicated that their technique is to use software-as-a-service cloud suppliers the place doable (e.g., particular functions from firms like Salesforce and SAP), thus minimizing the necessity to develop their very own in-house cloud experience. Since “Purchase earlier than construct; solely construct software program associated to your core competence” is a vital precept in any digital transformation, we anticipated to see a higher funding in software-as-a-service merchandise. Maybe this quantity actually signifies that virtually any firm might want to construct software program round its core worth proposition.
Our respondents strategy cloud migration aggressively. Nearly half (48%) stated they plan emigrate 50% or extra of their functions to the cloud within the coming yr; the most important group (20%) stated they plan emigrate 100% of their functions. (We surprise if, for a lot of of those respondents, a migration was already in progress.) 16% stated they plan emigrate 25% of their functions. 36% answered “not relevant,” which can imply that they aren’t utilizing the cloud (although this may point out a lot decrease cloud utilization than different questions do) or that the respondent’s group has already moved its functions to the cloud. It’s in all probability a mixture of each.

When requested particularly about cloud native improvement (constructing software program to run in a scalable cloud surroundings, whether or not that cloud is public, non-public, or hybrid), there was a fair break up between those that haven’t any plan to go cloud native, respondents representing companies which can be already 100% cloud native, and respondents who thought they might be cloud native sooner or later sooner or later. Every group was (very) roughly a 3rd of the full. Trying in additional element at respondents who’re within the technique of going cloud native, solely 6% count on to be cloud native inside a yr. The biggest group (20%) stated they’d be cloud native inside three or extra years, indicating a common route, if not a selected purpose.
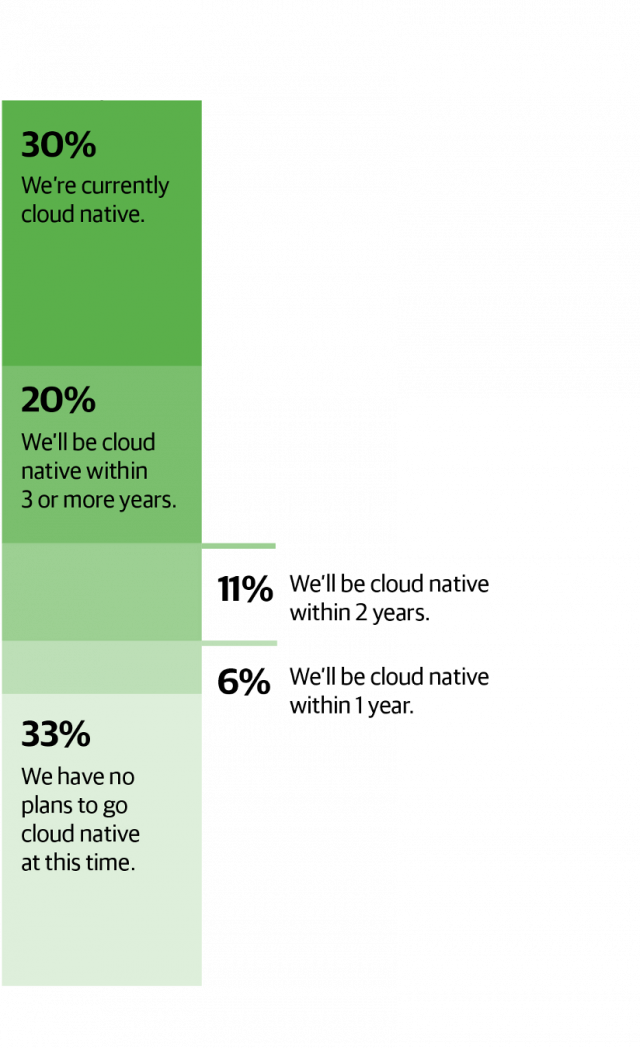
Does the 67% who’re planning to be or are already cloud native battle with the 47% who stated that they’re pursuing a cloud first technique? It’s jarring—“cloud native” is, if something, a stronger assertion than “cloud first.” Presumably anybody who works for a corporation that’s already cloud native can be pursuing a cloud first technique. Among the hole disappears if we embody respondents executing a multicloud technique within the “cloud first” group, which brings the “cloud first” complete to 57%. In spite of everything, “cloud native” as outlined by Wikipedia explicitly consists of hybrid clouds.
Maybe extra to the purpose: there’s a whole lot of latitude in how respondents may interpret slogans and buzzwords like “cloud native” and “cloud first.” Somebody who says that their group might be “cloud native” sooner or later sooner or later (whether or not it takes one yr, two years, or three or extra years) isn’t saying that there aren’t vital noncloud initiatives in progress, and three or extra years hardly units an formidable purpose. However no matter how respondents might have understood these phrases, it’s clear {that a} substantial majority are transferring in a route that locations all of their workloads within the cloud.
Value and different points
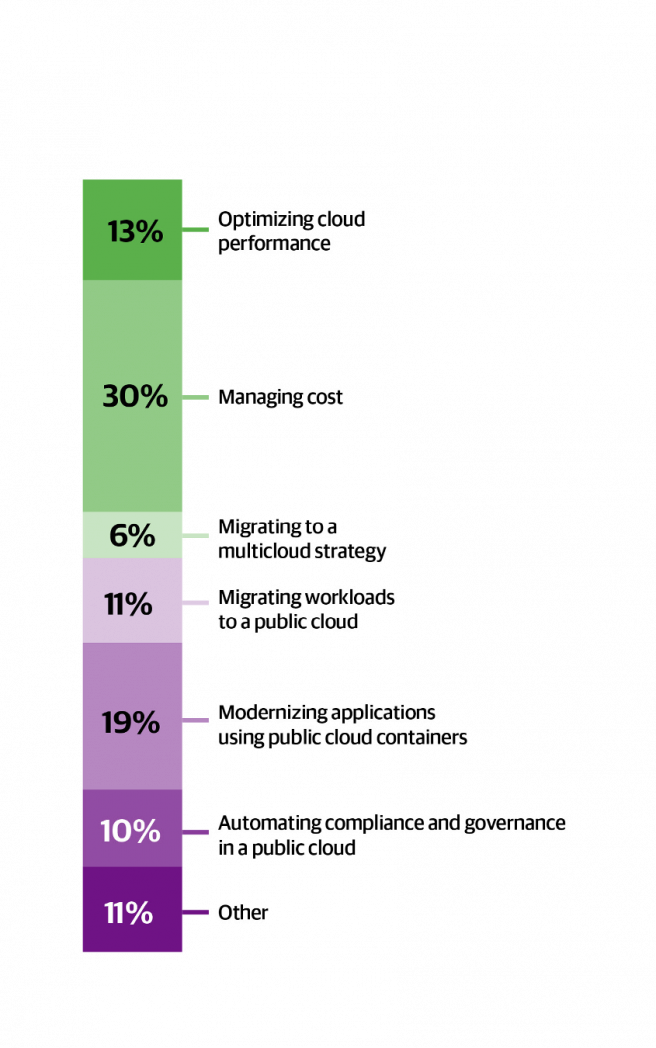
Survey respondents constantly reported that value is a priority. When requested about a very powerful initiatives of their organizations pertaining to public cloud adoption, 30% of all respondents stated “managing value.” Different necessary cloud initiatives embody efficiency optimization (13%), modernizing functions (19%), automating compliance and governance (10%), and cloud migration itself (11%). Solely 6% listed migrating to a multicloud technique as a problem—stunning given the massive quantity who stated they’re pursuing hybrid cloud or multicloud methods.
These outcomes had been comparable throughout all industries. In virtually each sector, managing value was perceived as a very powerful cloud initiative. Authorities and finance & banking had been outliers; in these sectors, modernizing functions was a higher concern than value administration. (23% of the respondents within the authorities sector listed modernization as a very powerful initiative, as did 21% of the respondents from finance & banking.)
Amongst respondents who aren’t utilizing cloud computing, 21% stated that regulatory necessities require them to maintain knowledge on-premises; 19% stated that value is a very powerful issue; and 19% had been involved with the chance of migration. Comparatively few had been involved concerning the availability of expertise (6%, in sharp distinction to our 2021 Information/AI Wage Survey outcomes), and 5% stated vendor lock-in is a priority. Once more, this aligns effectively with our outcomes from 2020: conserving knowledge on-premises was the most typical cause for
not utilizing cloud computing, and price was the second, adopted by migration threat.
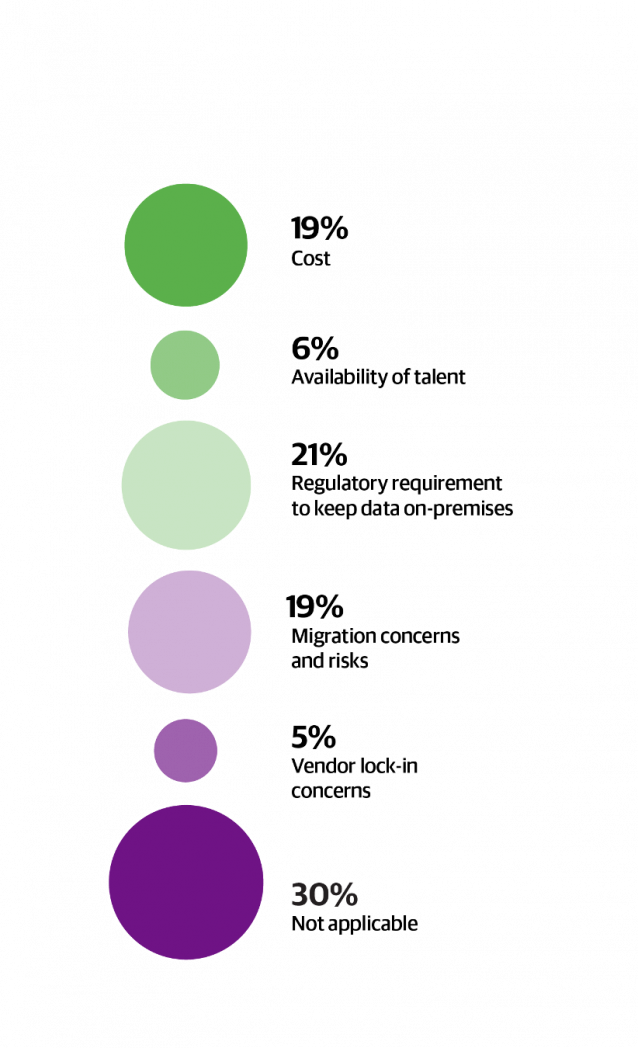
Why is value such a crucial issue? It’s straightforward to get into cloud computing on a small scale: constructing some experimental apps within the cloud as a result of you’ll be able to lease time utilizing an organization bank card fairly than going by IT for extra sources. If profitable, these functions develop into actual software program investments that it’s good to assist. They begin to require extra sources, and because the scale grows, you discover that your cloud supplier is getting the “economies of scale,” not you. Cloud suppliers definitely know tips on how to set pricing in order that it’s straightforward to maneuver in however tough to maneuver out.
So, sure, value must be managed. And one solution to handle cloud value is to remain away. You’re not locked right into a vendor in case you don’t have a vendor. However that’s a simplistic reply. Good value administration must account for the true advantages of transferring to the cloud, which normally don’t contain value. By analogy, meeting strains didn’t reduce the price of constructing a manufacturing unit; they made factories more practical. The cloud’s capability to scale shortly to deal with sudden adjustments in workload is price so much. Do your functions immediately develop into sluggish if there’s a sudden spike in load, and does that trigger you to lose gross sales? In 2021, “Please be affected person; our techniques are experiencing heavy load” tells prospects to go elsewhere. Improved uptime can be price so much; cloud suppliers have a number of knowledge facilities and backup energy that almost all companies can’t afford. (At O’Reilly, we realized this firsthand throughout the California fires of 2019, which disabled our on-premises infrastructure. We’re now 100% within the cloud, and we’re positive different firms realized the identical lesson.)
Regulatory necessities are a giant concern for respondents who aren’t utilizing cloud computing (21%). Once we take a look at respondents as an entire, although, we see one thing totally different. In most industries, roughly 10% of the respondents listed regulatory compliance as a very powerful initiative. Probably the most notable outliers had been finance & banking (15%), authorities (19%), and healthcare (19%)—however compliance nonetheless wasn’t the most important concern for these industries. Respondents from the upper schooling sector reported little concern about compliance (4.8%). Different industries that had been comparatively unconcerned about compliance included electronics & {hardware} and media & leisure (each 3.8%). Though we’re shocked by the responses from greater schooling, on the entire, these observations make sense: compliance is a giant subject for industries which can be closely regulated and fewer of a problem for industries that aren’t. Nevertheless, it’s additionally necessary to watch that concern about compliance isn’t stopping closely regulated industries from transferring to the cloud. Once more, regulatory compliance is a priority—however that concern is trumped by the necessity to present new sorts of functions.
Expertise
Though solely 6% of the respondents who aren’t utilizing cloud computing stated that talent availability was a problem, we’re skeptical about that—in case you’re not transferring to the cloud, you don’t want cloud expertise. We bought a unique reply once we requested all respondents what expertise had been wanted to develop their cloud infrastructure. (For this query, respondents had been allowed to decide on a number of choices.) The commonest response was “cloud-based safety” (59%; over half of the respondents), with “common cloud information” second (54%). That’s an excellent signal. Organizations are lastly waking as much as the truth that safety is important, not one thing that’s added on if there’s time.
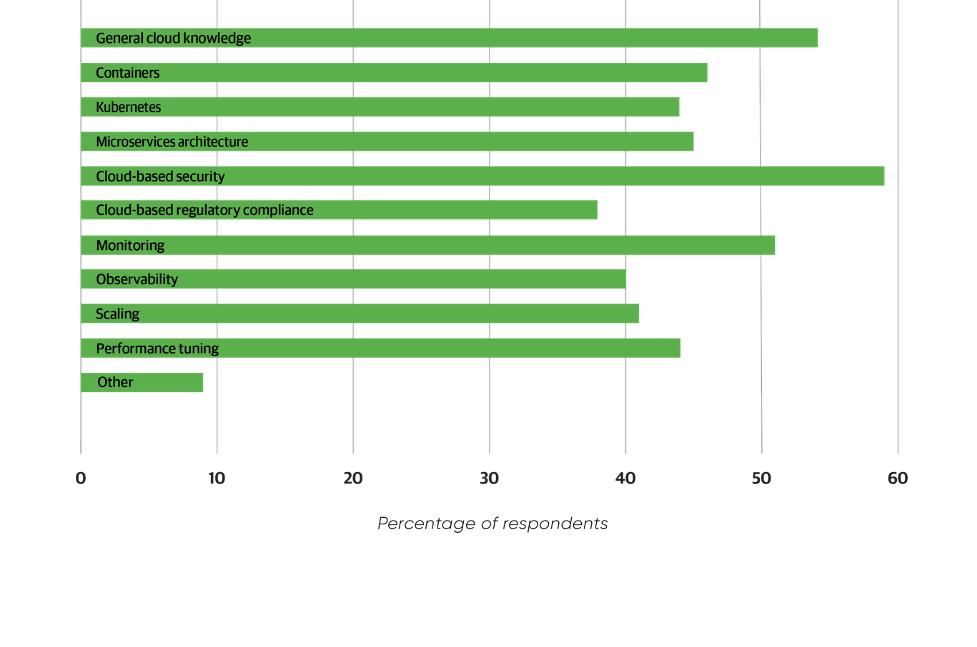
Maybe the most important factor to be taught from this query, although, is that over 35% of the respondents chosen the entire expertise (besides different”). Most of them had been round 45%. Containers (46%), Kubernetes (44%), microservices (45%), compliance (38%), monitoring (51%), observability (40%), scaling (41%), and efficiency (44%) are all on this territory. Our respondents look like saying that they want every part. All the abilities. There’s positively a scarcity in cloud experience. In our not too long ago printed 2021 Information/AI Wage Survey report, we famous that cloud certifications had been most related to wage will increase. That claims so much: there’s demand, and employers are prepared to pay for expertise.
Portability between clouds
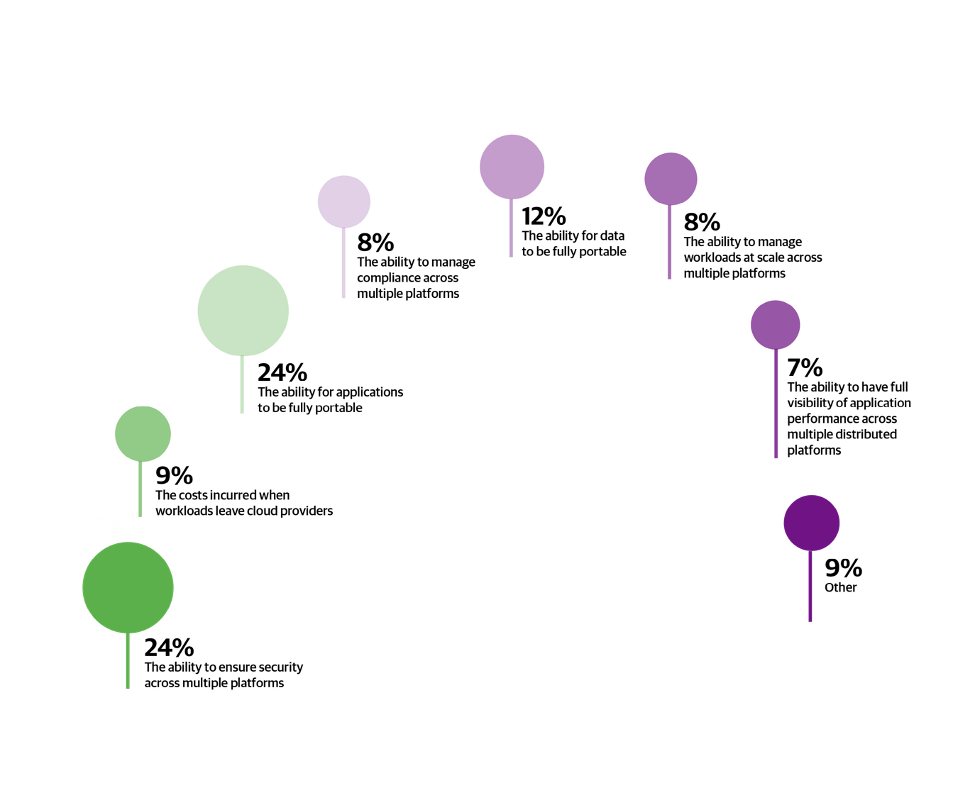
Our remaining query regarded ahead to the following era of cloud computing. We requested concerning the limitations to transferring workloads freely between cloud deployment platforms: what it takes to transfer functions seamlessly from one cloud to a different, to a personal cloud, and even to conventional infrastructure. That’s actually the purpose of a hybrid cloud.
Software portability and safety had been the most important issues (each 24%). The necessity for portability is apparent. However what might lie behind concern over portability is the string of improvement platforms which have promised software portability, going again a minimum of to Digital Tools’s CORBA in 1991 (and probably a lot earlier). Containers and container orchestration are themselves “write as soon as, run wherever” applied sciences. Net Meeting (Wasm) is the present fashionable try to search out this holy grail; we’ll discover out within the coming years whether or not it suffices.
Safety on one platform is difficult sufficient, and writing software program that’s safe throughout a number of execution environments is rather more tough. With the rising variety of high-profile assaults towards giant companies, executives have a proper to be involved. On the similar time, each safety professional we’ve talked to has emphasised that a very powerful factor any group can do is to concentrate to the fundamentals: authentication, authorization, software program replace, backups, and different facets of safety hygiene. Within the cloud, the instruments and methods used to implement these fundamentals are totally different and arguably extra complicated, however the fundamentals stay the identical.
Different issues all clustered round 10%: probably the most vital embody knowledge portability (12%), necessary and infrequently ignored; the price of transferring knowledge out of 1 cloud supplier into one other (9%), a priority we noticed elsewhere on this examine; managing compliance and, extra typically, managing workloads at scale throughout a number of platforms (each 8%); and visibility into software efficiency (7%).
Till subsequent yr
What did we be taught? Cloud adoption continues, and it doesn’t seem to have been affected by the pandemic. Roughly 90% of our respondents work for organizations which can be transferring functions to the cloud. This share is barely barely bigger than final yr (88%) and will not even be vital. (However take into account that once you’re at 90%, any additional positive aspects include nice problem. In observe, 90% is about as near “everyone” as you will get.)
We additionally consider that we’re solely on the starting of cloud adoption. Our viewers is technically subtle, and so they’re extra more likely to be cloud adopters. A big majority of the respondents are within the technique of transferring functions to the cloud, indicating that “cloud” is a piece in progress. It’s clearly a state of affairs by which the extra you do, the extra you see that may be performed. The extra workloads you progress to the cloud, the extra you notice that different workloads can transfer. Extra necessary, the extra comfy you’re with the cloud, the extra revolutionary you may be in pushing your digital transformation even additional.
Issues about compliance stay vital. Not surprisingly, these issues are greater amongst respondents who aren’t utilizing the cloud than amongst those that are. That’s pure—however trying on the fast tempo of cloud adoption in closely regulated industries like finance & banking makes us assume that “compliance” is extra of an excuse for noncloud customers than an actual concern. Sure, compliance is a matter, however it’s a problem that many organizations are fixing.
Managing prices is clearly an necessary concern, and in contrast to compliance, it’s a concern ranked extra extremely by cloud customers than nonusers. That’s each regular and wholesome. The frequent notion that cloud computing is cheap isn’t actuality. With the ability to allocate a couple of servers or high-powered compute engines with a bank card is definitely an affordable solution to begin a challenge, however these financial savings evaporate at enterprise scale. The cloud supplier will reap the economies of scale. For a consumer, the cloud’s actual benefits aren’t in value financial savings however in flexibility, reliability, and scaling.
Lastly, cloud expertise are in demand throughout the board. Common expertise, particular experience in areas like safety, microservices, containers, and orchestration—all are wanted. Whether or not or not there’s a scarcity of cloud experience within the job market, this is a wonderful time to pursue coaching alternatives. Many organizations are coping with the query of whether or not to rent or practice their employees for brand new capabilities. When pursuing a cloud transformation, it makes eminent sense to depend on builders who already perceive your small business and your functions. Hiring new expertise is at all times necessary, however giving your present employees new expertise could also be extra productive in the long term. If your small business goes to be a cloud enterprise, then your software program builders have to develop into cloud builders.
Footnote
- A short word about precision. We’ve rounded percentages to the closest 1%, besides in some circumstances the place the share is small (underneath 10%). With almost 3,000 respondents, 0.1% solely represents 3 customers, and we’d argue that drawing conclusions based mostly on a distinction of a share level or two is misusing the information.
[ad_2]

